Development of AI-Driven Financial Insight Tool in MOVA

Emmanuel


An AI agent that reasons over someone's real accounts, obligations and income pattern to answer one question: how much of this is actually mine to spend right now?
Role
Designer and builderYear
Product strategy, UX research, AI interaction design, design system, coded prototype
Beta, round one with seven testers
Home: Safe-to-Spend up top, a nudge from MOVA, and a question one tap away.
Problem
Most Nigerians can check their balance, but almost none can say with confidence how much of it is theirs to spend right now.
Solution
An AI agent that reasons over real accounts, obligations and income patterns, backed by a visible six-level permission ladder.
Result
Tester confidence rose from 3.3 to 4.3, and the biggest jump came from the irregular-income tester the scope call was fought for.
Confidence in knowing what's safe to spend, up from 3.3
The irregular-income tester, up from 1 out of 5
On this page
Most Nigerians can check their balance. Almost none can answer, with confidence, “how much of that is actually mine to spend right now.” I built MOVA to close that gap — not with a prettier budget screen, but with an AI agent that reasons over someone's real accounts, real obligations, and real income pattern, and is honest about what it can't yet do.
The problem
Nigeria's financial-inclusion numbers look like progress until you sit with them. Formal inclusion rose to 64% in 2023 — but financial health fell over the same period, and 76.7% of employed Nigerians earn informally, meaning income that doesn't land on the same date every month. Every AI-finance app I researched, including the best ones built abroad, quietly assumes a salaried, monthly, single-currency life. That assumption was the actual gap. A nicer-looking budget app was never the brief.
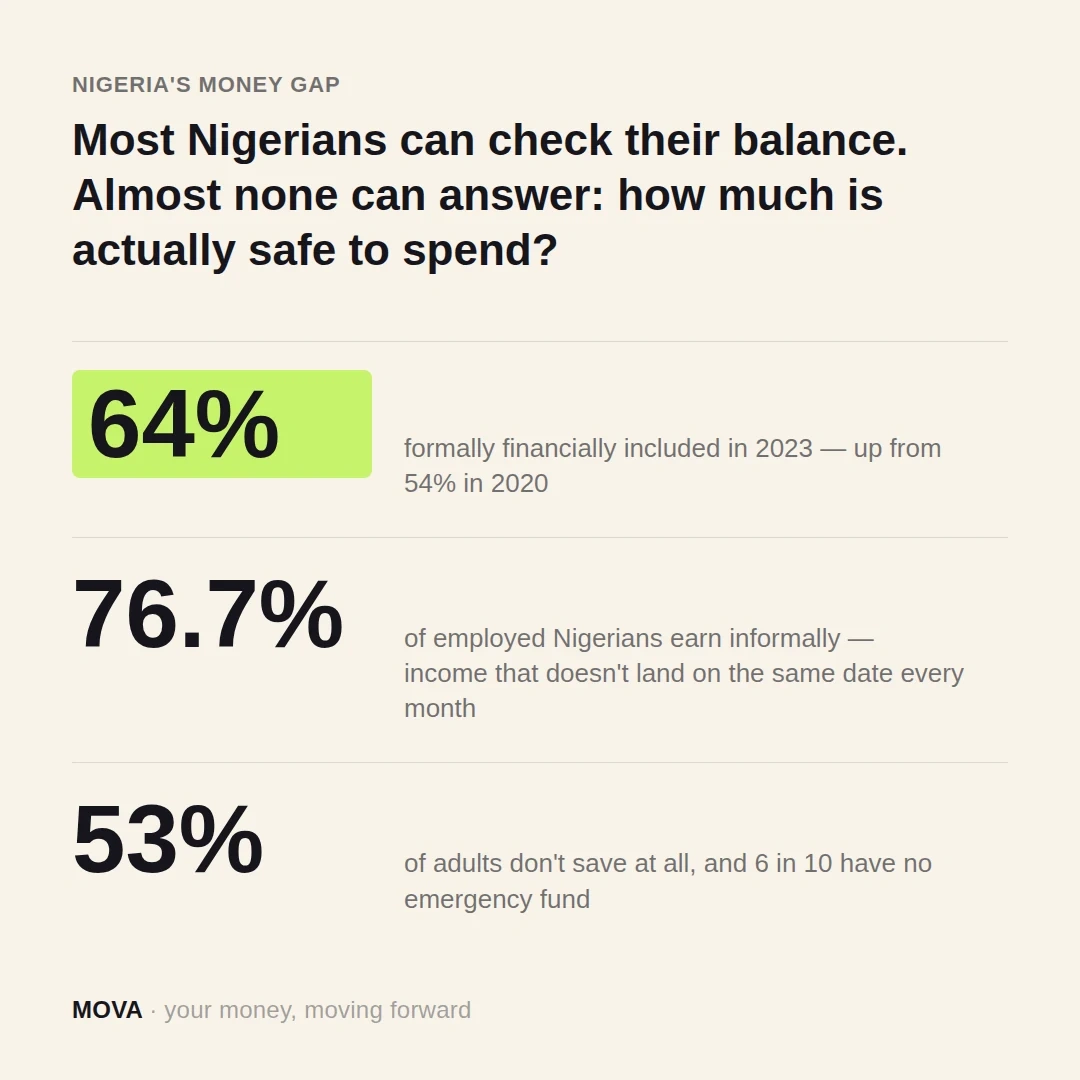
Money Gap in three stats
What already existed didn't fit
Before drawing a screen, I tore down three of the strongest AI-finance apps shipping today. Cleo proves an AI can hold a real seat in primary navigation without turning into a generic chatbot. Copilot Money proves restraint and structure can carry an entire product. Monarch proves that classifying obligations by behavior — Fixed, Non-Monthly, Flexible — beats classifying by type. None of the three has a real answer for irregular income, multiple wallets, or family obligations as their own transaction category. That's the gap MOVA is built to fill, and it's one the teardown surfaced structurally, not from a hunch.
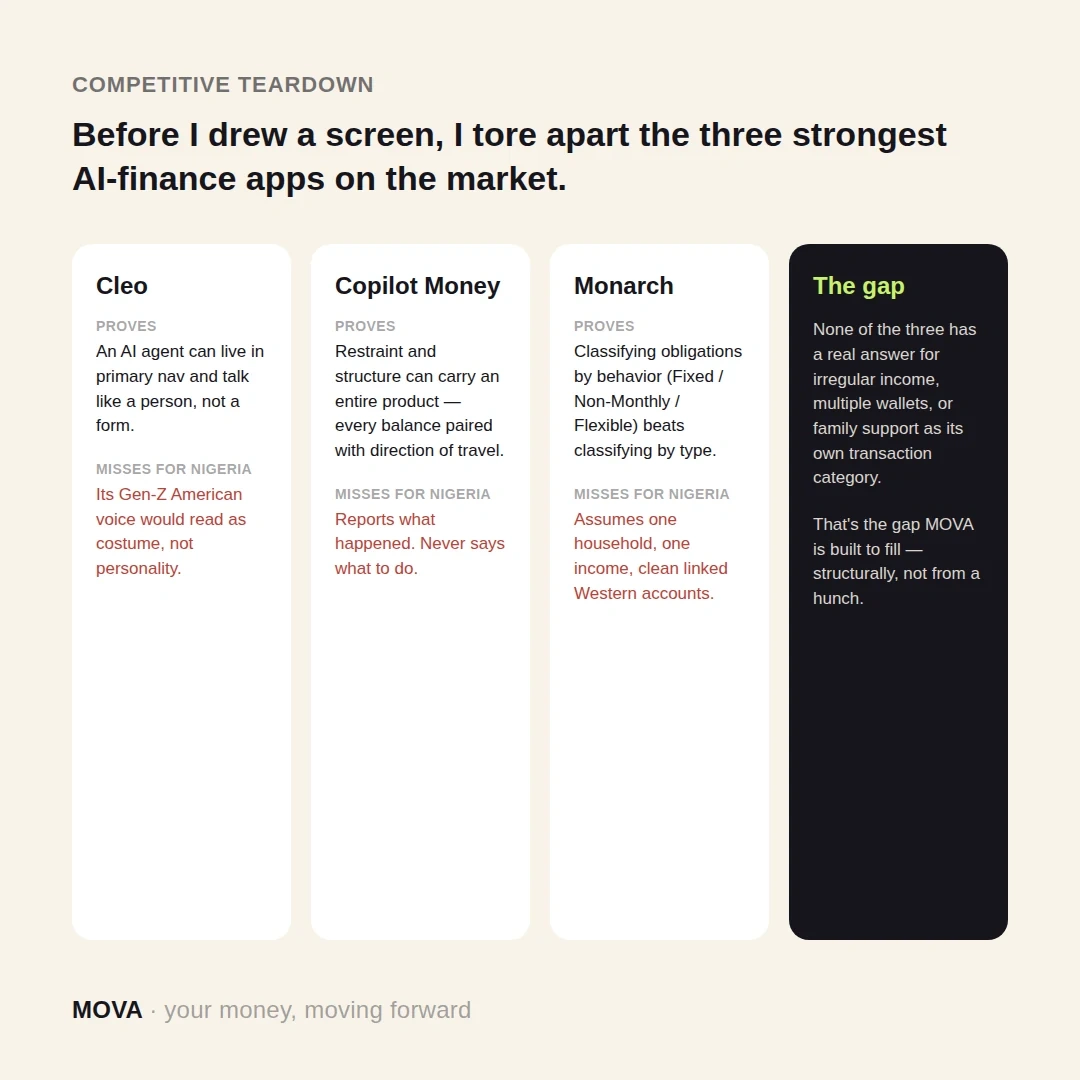
Competitive teardown: Cleo, Copilot Money, Monarch
The core idea
Most finance apps blur a distinction on purpose: balance, available money, and Safe-to-Spend are three different numbers, and only the third one answers the question people actually have. Safe-to-Spend nets out what's already committed, what's earmarked toward a goal, and a protective buffer — and only then tells you what's genuinely yours to spend today. It's the only number in the product allowed to render at Display size, and every other screen either feeds this calculation or explains a consequence of it.
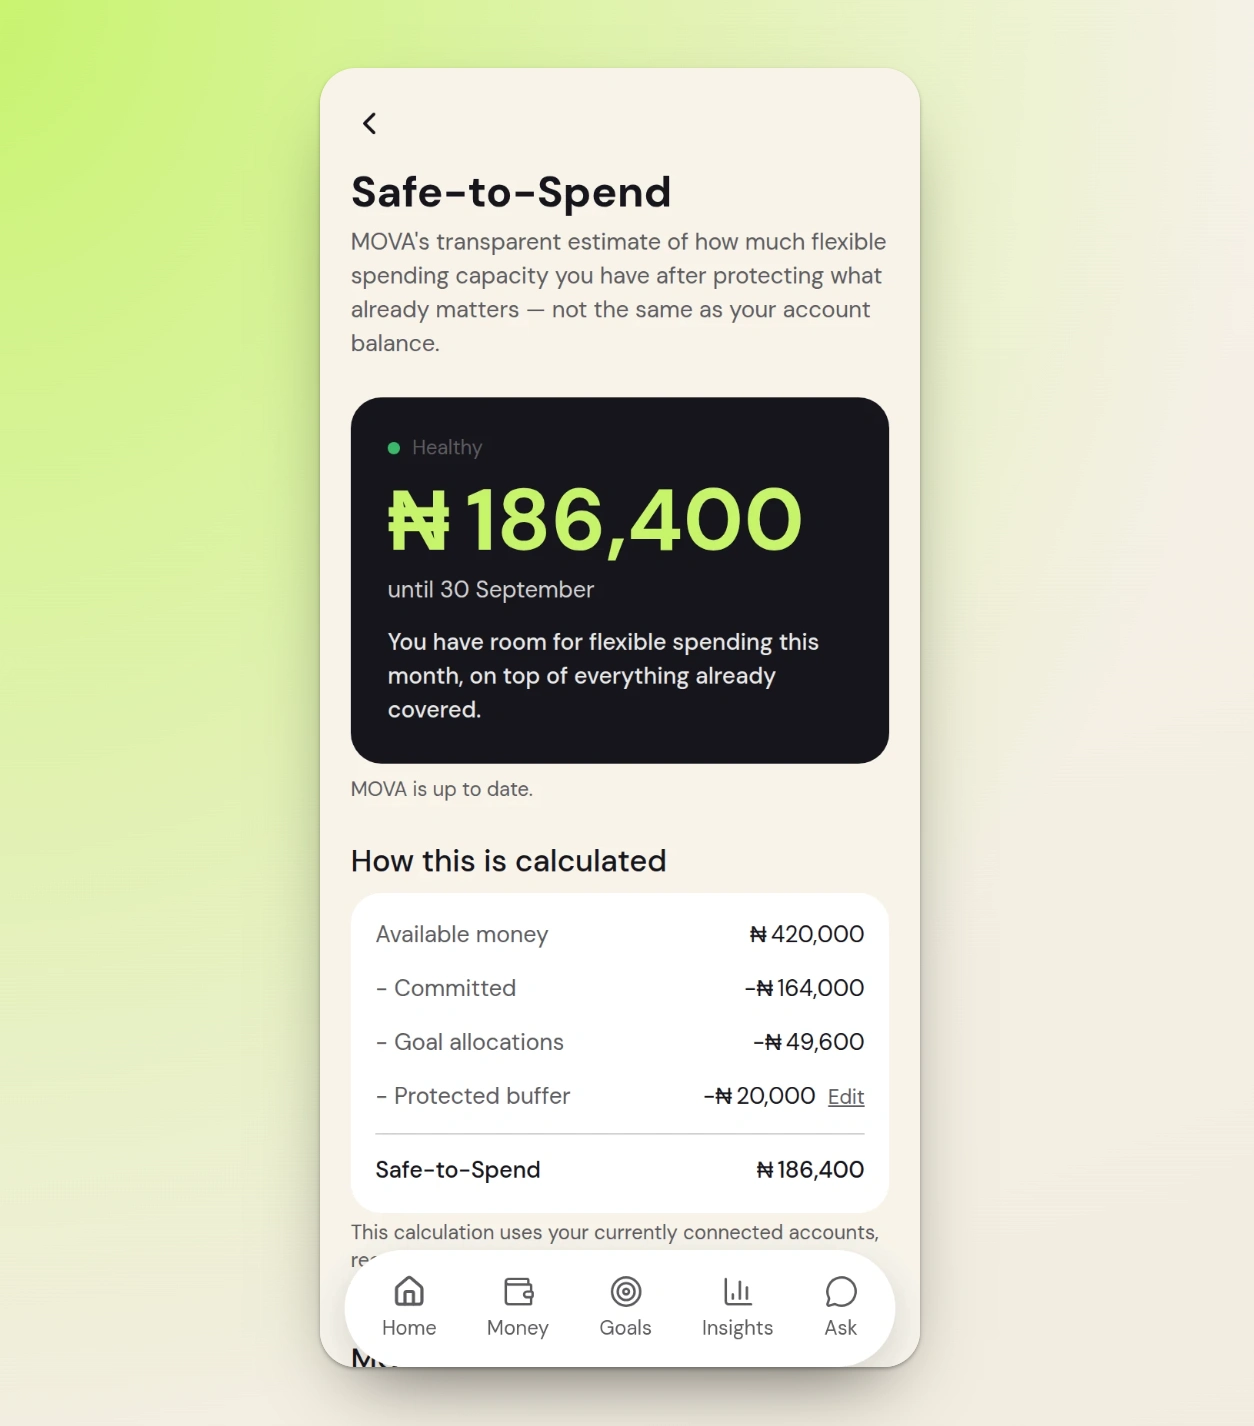
The Safe-to-Spend screen
Designing for trust, not just utility
The hardest problem wasn't the calculation — it was the permission model. In a market where trust in any app touching your money starts from a lower baseline, an AI feature is a liability unless permission is core product, not a settings-page afterthought. I built a six-level AI interaction ladder — Inform, Explain, Recommend, Prepare, Confirm, Automate — and every AI-initiated action in MOVA sits at exactly one level, visibly. Nothing touching real money moves without an explicit tap anywhere in V1 or V2; automation is opt-in per rule, never on by default, and fully reversible.
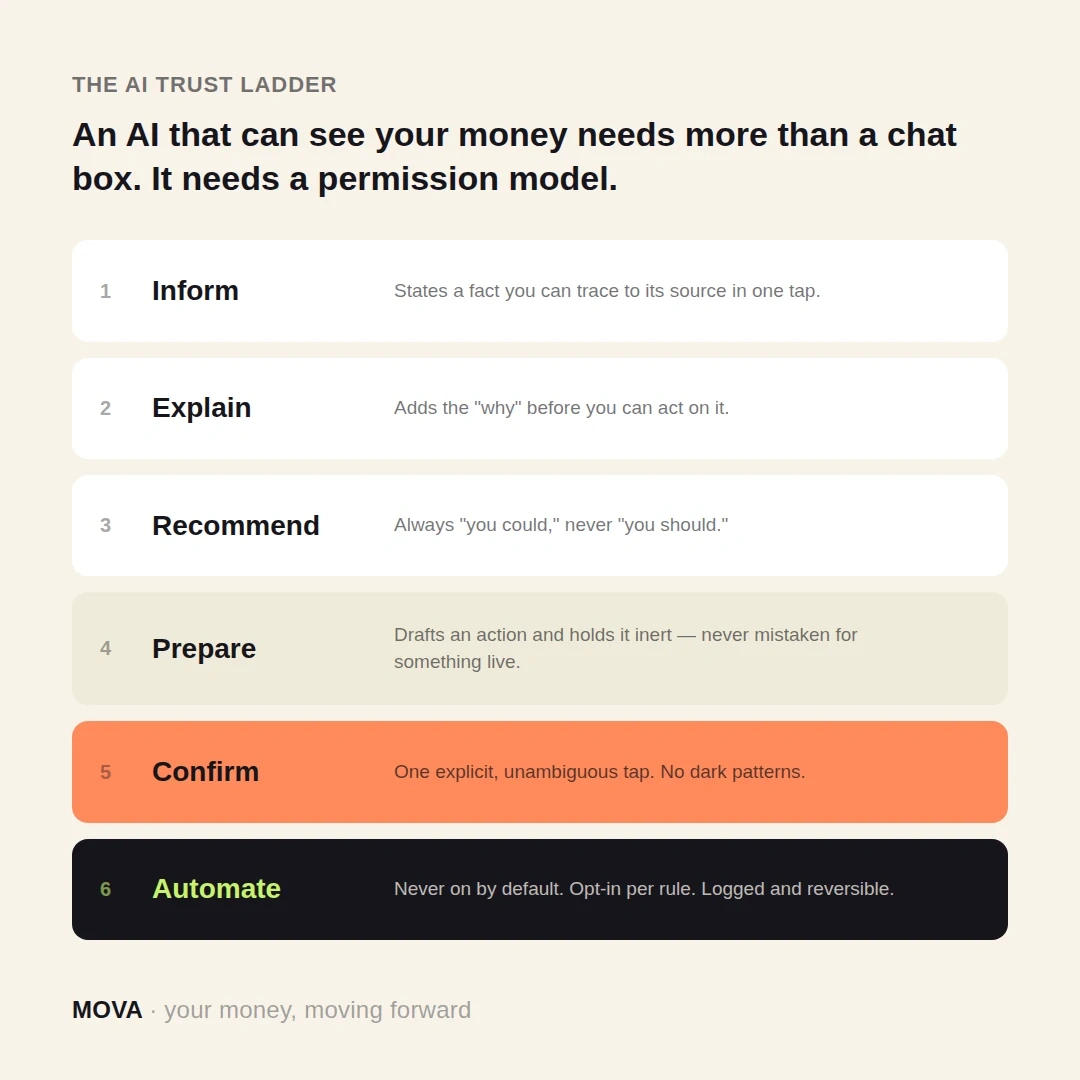
The six-level AI trust ladder
A quick look at the product
Five tabs organized around outcomes a user actually has — Home, Money, Goals, Insights, Ask — rather than data objects. A 22-screen build across nine flows, held disciplined enough that Insights and Ask MOVA each shipped without adding a single new destination screen.
A quick look at MOVA
Scope, defended with a reason
Nothing in the roadmap is there because it's easy to draw. The original brief placed Irregular Income Mode in V2. I moved it into V1, against the brief, because 76.7% of the workforce is informal and a V1 that assumes a fixed paycheck would fail most of the addressable market on day one. What stayed in V2 was the sophistication — forecasting, confidence bands — not the baseline ability to function without one.
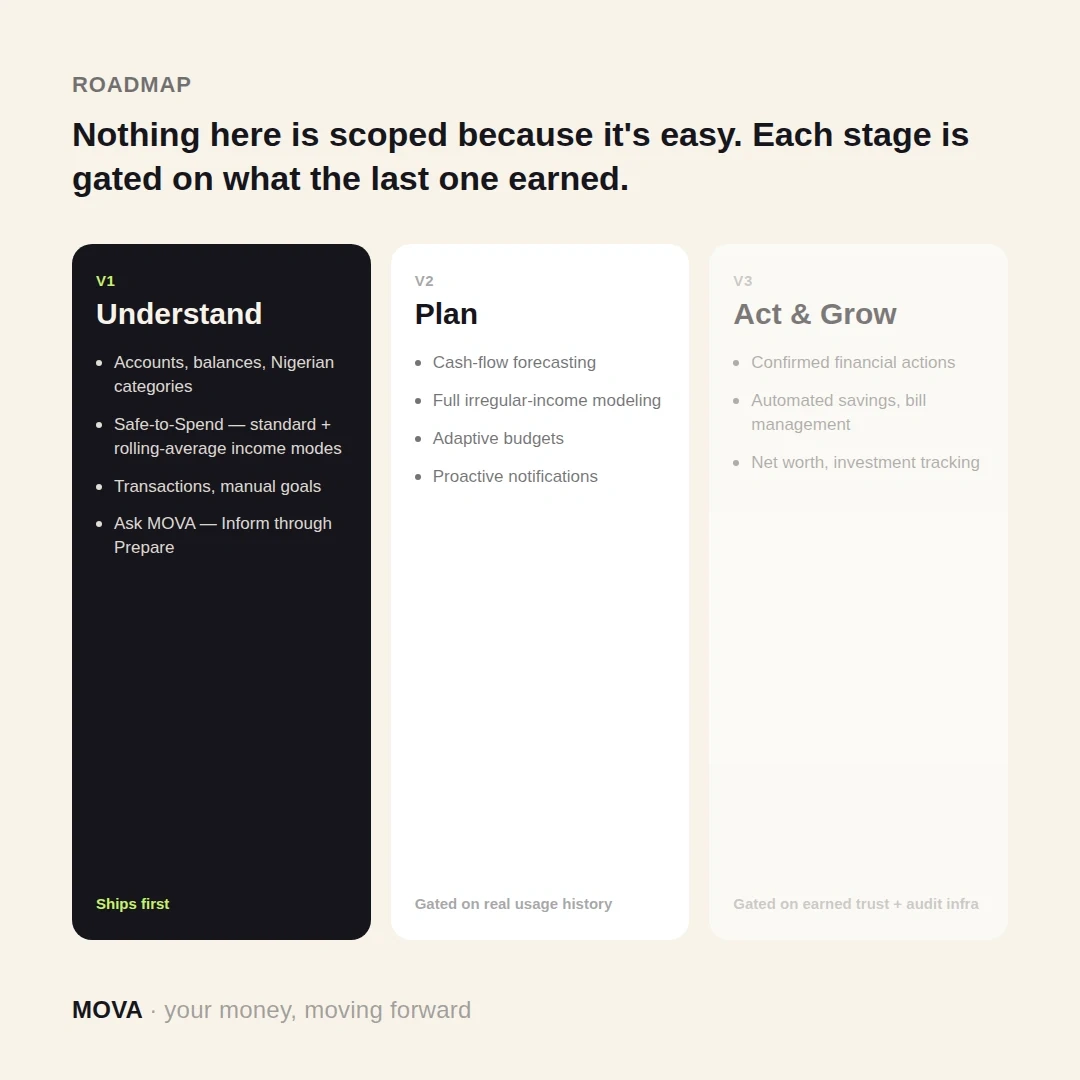
V1 to V2 to V3 roadmap
Challenges
Betting against the brief.
Pulling Irregular Income Mode forward was a real risk — it meant defending a scope change with a research citation instead of a gut feeling, before a single user had touched the product to confirm it was right.
Trust turned out to be two problems, not one.
I'd designed one permission ladder for what the AI does with your data. Beta testing surfaced a second, separate question I hadn't fully designed for: whether someone trusts the app enough to hand over real bank details in the first place. Those needed different answers, and only one of them had one going in.
Ask MOVA broke for every single beta tester.
Five of seven testers tried it; all five hit a production failure. I traced it to the Anthropic account behind the API key running out of credit — not a code bug, a billing lapse the code's own error handling didn't distinguish from an actual outage. I fixed the error handling to name that failure clearly, reproduced the fix live against production to confirm it, and it's now a standing check before any future test round: hit the live endpoint once before testers do, don't assume it works because it did last time.
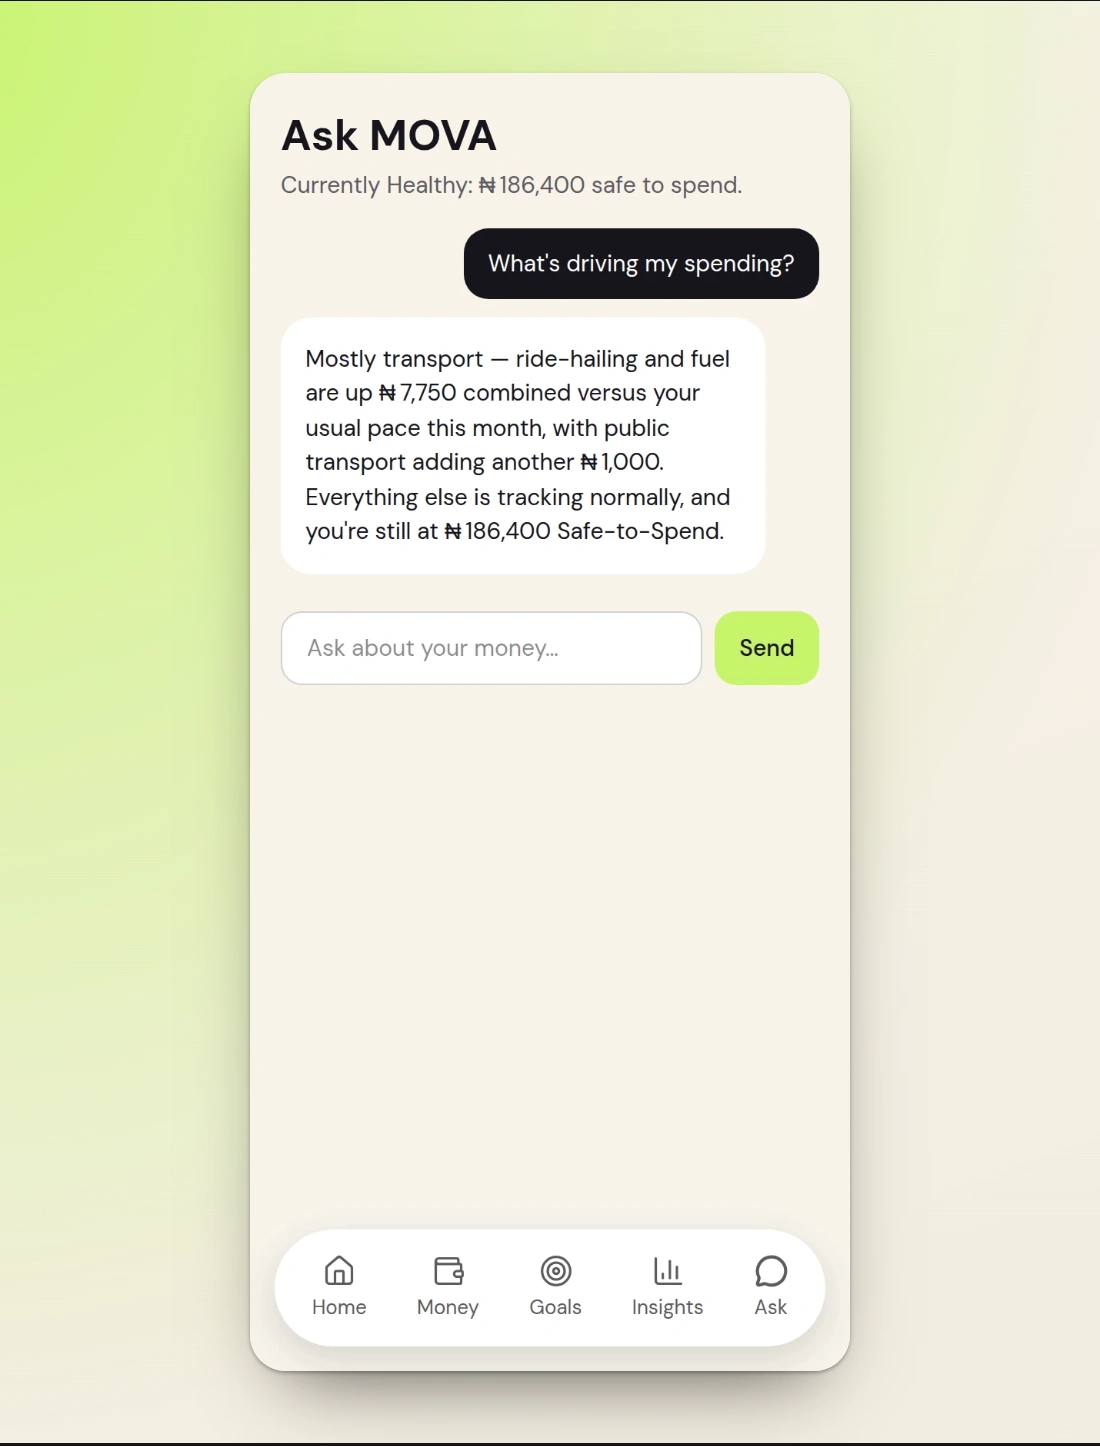
Ask MOVA, the flow that broke.
What testing actually showed
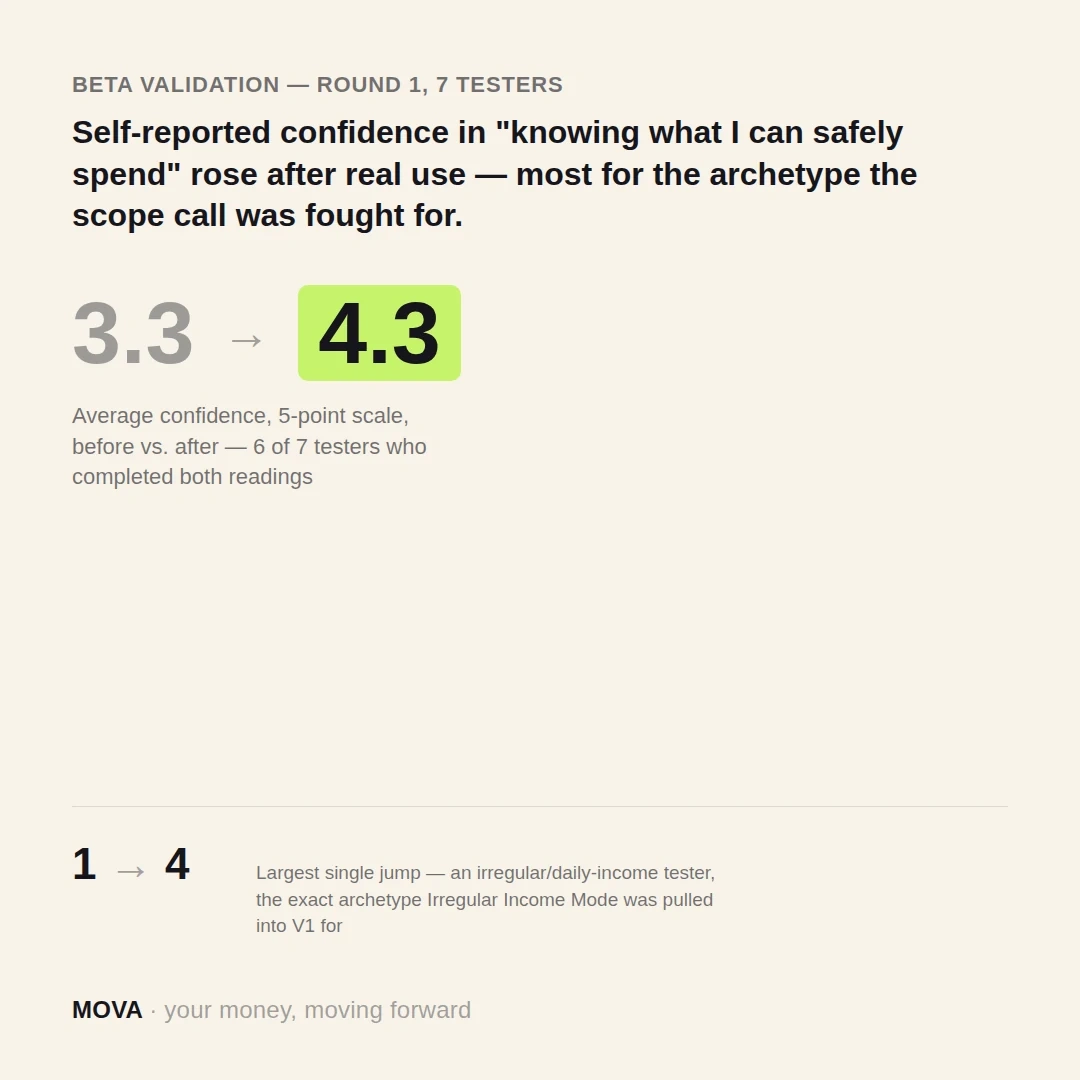
Confidence rose from 3.3 to 4.3, with a 1 to 4 standout jump
Self-reported confidence in “knowing what I can safely spend” rose from 3.3 to 4.3 (five-point scale) across six testers who completed both readings. The single largest jump belonged to an irregular-income tester — 1 out of 5 before, 4 out of 5 after — the exact archetype the scope call was fought for. One data point doesn't prove a strategy, but it's the strongest evidence available that the call was right.
Lessons learned
A correct answer can still feel wrong.
MOVA's color system reserves red for true failures and renders a negative balance in orange, by design. One tester still described seeing “-₦18,000” as feeling like she was “in debt or overspending.” The math and the color were both right; the number's emotional weight didn't fully go away because of it — a genuine open design question, not a bug a hex code fixes.
Trust isn't one dial.
Watching real people react is what surfaced that “trusting the AI” and “trusting the app with my data” are separate decisions — something a heuristic review of my own designs never would have caught.
Test the plumbing before the people.
The Ask MOVA outage should have been one test call away from being caught before a single tester hit it. It's now a standing habit, not an assumption.
A scope bet stays a bet until data closes it.
Moving Irregular Income Mode into V1 was the right call on paper. It only became a validated call once an actual irregular-income user's own confidence score confirmed it.
What's next
A second beta round targeting more irregular-income and salaried-budgeter testers specifically, now that Ask MOVA is reliable — to see whether these early patterns hold at slightly larger numbers.
See it in motion
Everything above in static screens, run back to back. A full pass through Home, Money, Goals, Insights, Ask MOVA reasoning live over a real question, and the AI permission settings that back it.
MOVA, walked through end to end — coded prototype, not a click-through mockup.
Companion materials available on request: the full Figma file (every screen and state), and the underlying research and strategy documents this case study draws from.
Like this project
Posted Sep 29, 2026
Developed an AI agent in MOVA to enhance users' confidence in financial management.