Hân Phạm
Finance & Accounting Freelancer | Budgeting, Financial Analy


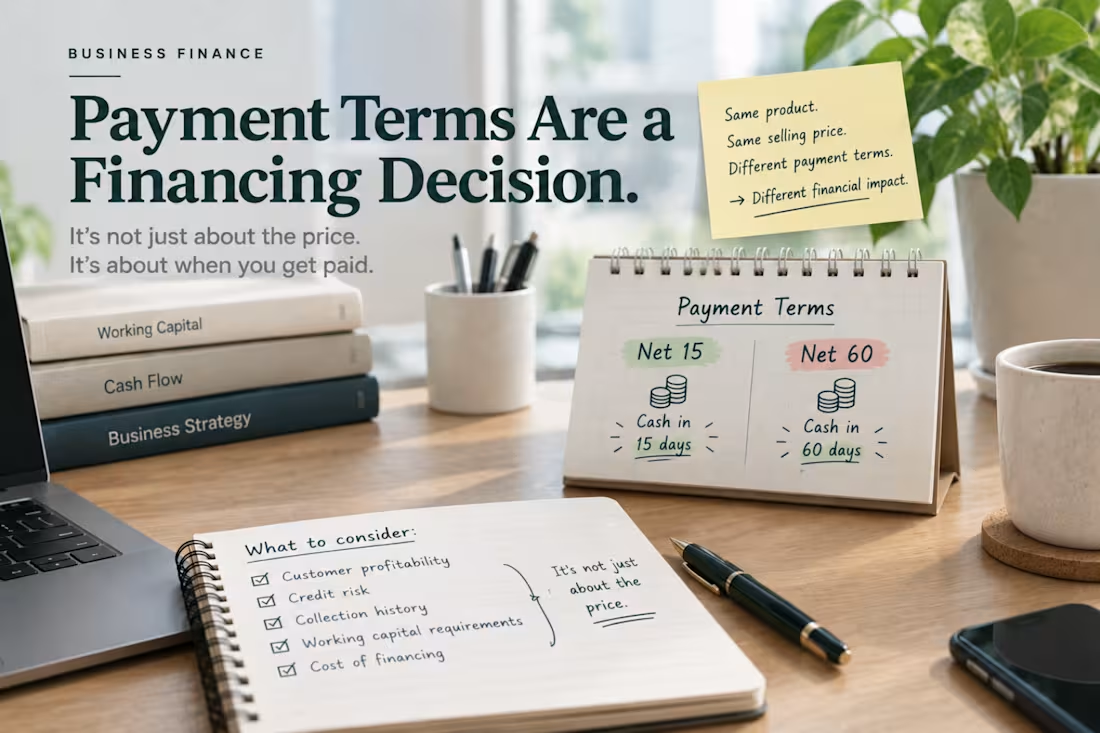
“Net 60” sounds like a payment term.
But financially, it can also be a financing decision.
Imagine you sell $100,000 of products to a customer.
They don't pay today.
They pay in 60 days.
That means your business may need to fund:
→ Inventory
→ Staff costs
→ Shipping
→ Supplier payments
→ Other operating expenses
for up to two months before receiving the cash from that sale.
Now imagine another customer offers to pay within 15 days.
Same product.
Same selling price.
But financially, the two customers aren't exactly the same.
The difference is how long your cash is tied up.
This is why payment terms should be considered alongside:
→ Customer profitability
→ Credit risk
→ Collection history
→ Working capital requirements
→ Cost of financing
For example:
Customer A generates $20,000 of gross profit but pays in 90 days.
Customer B generates $18,000 of gross profit but pays in 15 days.
The $2,000 difference in gross profit doesn't tell the whole story.
If serving Customer A requires the business to borrow money or carry significantly more working capital, the financing cost may change the economics.
So when negotiating a contract, the question shouldn't only be:
“What price can we get?”
It can also be:
“When do we actually get paid?”
Because revenue has a timing dimension.
And sometimes, the timing of the cash matters almost as much as the amount.
Do you think businesses pay enough attention to payment terms when evaluating a customer or contract?
#BusinessFinance #WorkingCapital #CashFlow #FinancialAnalysis #FPandA #BusinessStrategy #B2B #SmallBusiness
0
17
Not every variance deserves an investigation.
A budget says marketing expenses should be $20,000.
Actual spending comes in at $20,800.
That's a $800 variance.
Is it a problem?
Maybe.
But imagine the same business has a $5 million annual operating budget.
Spending $800 more may not deserve the same attention as a $20,000 unfavorable variance in another account.
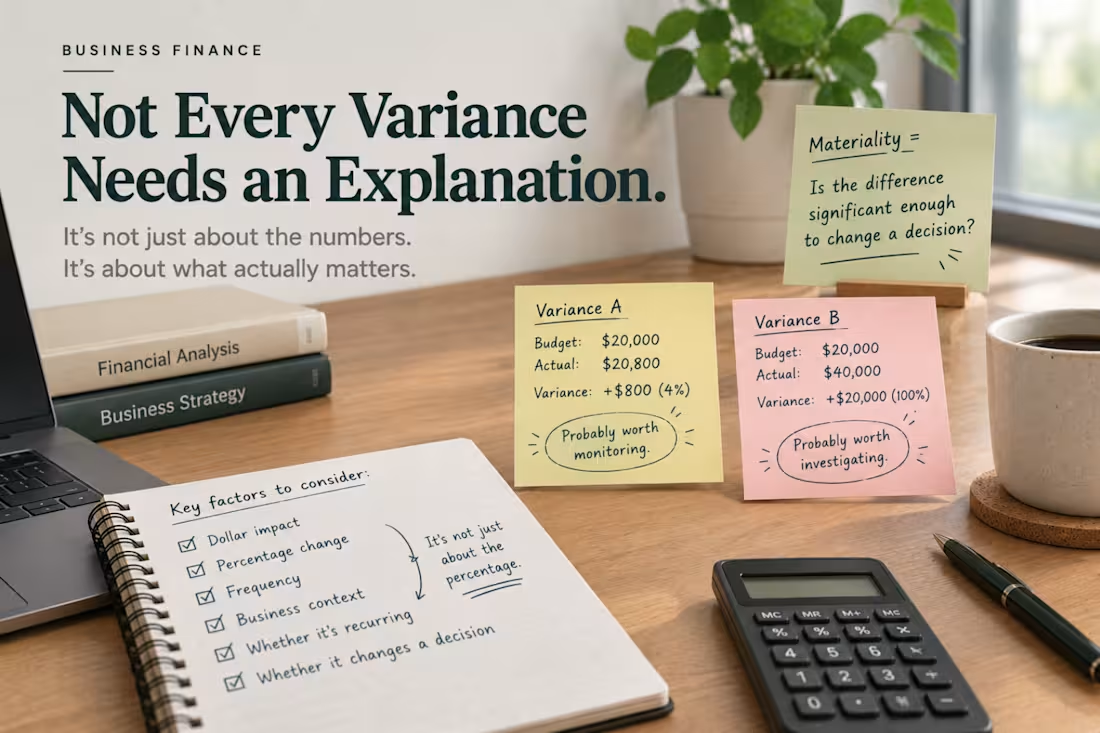
This is where materiality becomes useful.
Instead of asking:
“Why is the number different?”
Ask:
“Is the difference significant enough to change a decision?”
For example:
Variance A
Budget: $20,000
Actual: $20,800
Variance: +4%
→ Probably worth monitoring.
Variance B
Budget: $20,000
Actual: $40,000
Variance: +100%
→ Probably worth investigating.
But percentage alone isn't enough either.
A 50% variance on a $500 expense may matter less than a 5% variance on a $100,000 expense.
That's why a good variance review should consider:
→ Dollar impact
→ Percentage change
→ Frequency
→ Business context
→ Whether the variance is recurring
→ Whether it changes a decision
The goal of management reporting isn't to explain every number.
It's to identify the numbers that deserve attention.
Otherwise, finance teams can spend hours explaining small movements while missing the few variances that actually affect the business.
How does your team decide which variances are worth investigating?
#FPandA #FinancialAnalysis #ManagementReporting #BusinessFinance #VarianceAnalysis #Finance #BusinessStrategy #FinancialPlanning
0
13
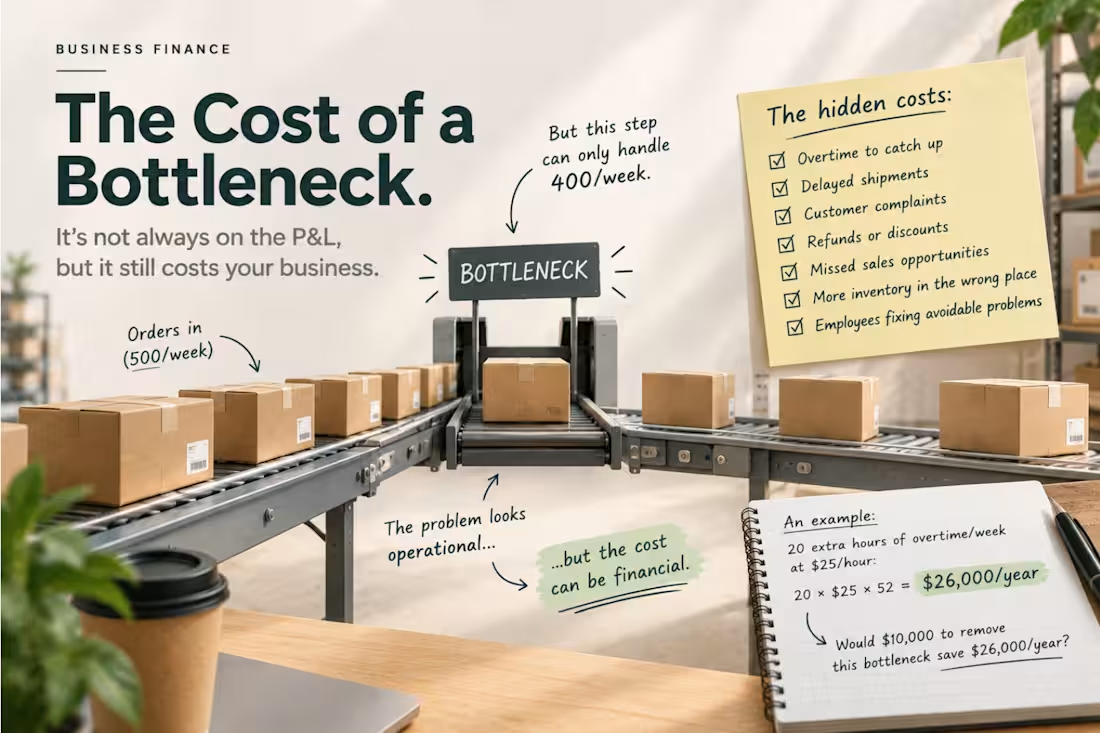
A bottleneck can cost your business money even when it doesn't appear on the P&L.
Imagine a business processing 500 orders per week.
One step in the process can only handle 400.
The immediate problem looks operational:
Orders are piling up.
But the financial impact can be much bigger.
That bottleneck might create:
→ Overtime to catch up
→ Delayed shipments
→ Customer complaints
→ Refunds or discounts
→ Missed sales opportunities
→ More inventory sitting in the wrong place
→ Employees spending time fixing avoidable problems
None of these may appear as a line called:
“Cost of Bottleneck.”
Instead, the cost gets scattered across several accounts.
This is why financial analysis shouldn't always start with the P&L.
Sometimes, you need to ask:
“Where is the process slowing down?”
Then connect the operational problem to the numbers.
For example:
If a process delay causes 20 extra hours of overtime each week at $25/hour:
20 × $25 × 52 = $26,000 per year
Suddenly, an “operations issue” has a measurable financial value.
And that changes the conversation.
Instead of:
“We need to work faster.”
You can ask:
“Would spending $10,000 to remove this bottleneck save $26,000 a year?”
That is a much more useful business decision.
The best financial analysis isn't always about finding where money was spent.
Sometimes, it's about finding where the business is losing capacity.
What operational bottleneck do you think businesses underestimate the financial cost of most?
#BusinessFinance #FinancialAnalysis #OperationsManagement #BusinessStrategy #ProcessImprovement #FPandA #SmallBusiness #OperationalEfficiency
0
23
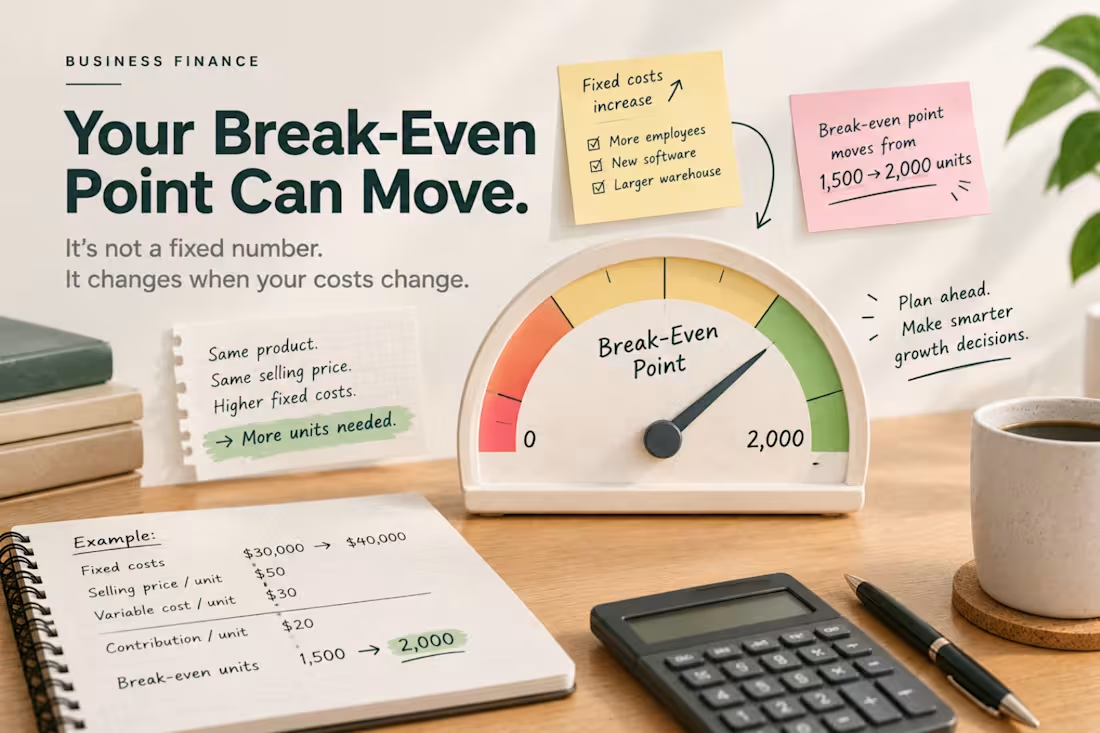
Your break-even point is not a fixed number.
Many businesses calculate it once:
“How much do we need to sell to cover our costs?”
Then they move on.
But the break-even point can change even when revenue hasn't.
Imagine a business with:
→ $30,000 monthly fixed costs
→ $50 selling price per unit
→ $30 variable cost per unit
Contribution per unit = $20.
So the business needs:
$30,000 / $20 = 1,500 units
to break even.
Now imagine the business hires two more employees, adds new software, and signs a larger warehouse contract.
Fixed costs increase to $40,000.
Nothing changed about the selling price.
Nothing changed about the product.
But the new break-even point is:
$40,000 / $20 = 2,000 units
The business now needs to sell 500 more units every month just to reach the same point where it stops losing money.
This is why growth decisions shouldn't only ask:
“Can we afford this expense?”
They should also ask:
→ How much does this increase our fixed cost base?
→ How much additional revenue do we need to support it?
→ How sensitive is profit if sales fall short?
→ At what sales level does the investment actually pay off?
A new office, employee, warehouse, or software system might create real value.
The question isn't whether the expense is “good” or “bad.”
The question is whether the business understands what level of activity is now required to support it.
Because every new fixed cost quietly raises the amount of business you need to do.
When your costs increase, do you recalculate your break-even point - or just update the budget?
#BusinessFinance #FinancialAnalysis #BreakEvenPoint #CostManagement #BusinessStrategy #FPandA #SmallBusiness #Finance
0
47