The network for creativity
Join 1.25M professional creatives like you
Connect with clients, get discovered, and run your business 100% commission-free
Creatives on Contra have earned over $150M and we are just getting started
Back to feedPost

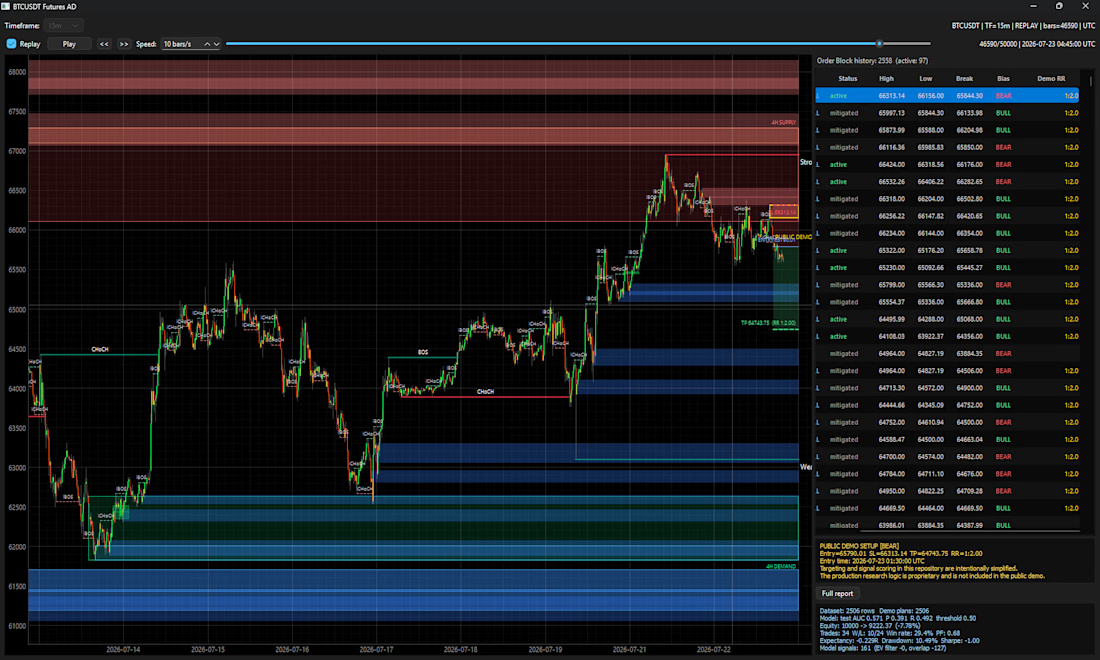
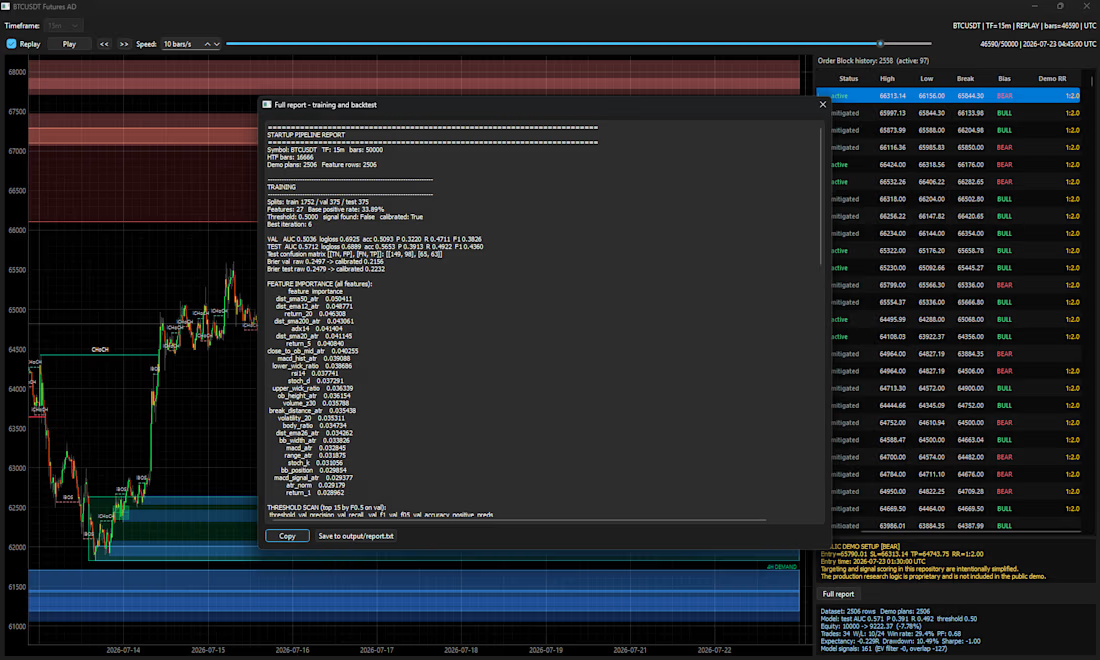
Built a quantitative research desktop pipeline that converts OHLCV data into causal SMC market-structure events, custom context/Volume Profile features and TP/SL-labelled datasets, then trains XGBoost with chronological train/validation/test splits, calibration, validation-only thresholding and leakage checks. The research layer is evaluated with realistic backtesting including fees, slippage, overlap control and equity risk sizing. The public demo preserves the architecture but replaces proprietary scoring, targets and features with generic examples.


The network for creativity
Join 1.25M professional creatives like you
Connect with clients, get discovered, and run your business 100% commission-free
Creatives on Contra have earned over $150M and we are just getting started

Challenges
View all


Related posts

Built From Motion And Light


NIGHTJAR as a real-time motion identity in WebGL is a bold way to do brand, and the dusk skyline with the film listing is a moody pick. Contrarian question: a brand that only exists in motion is brilliant on a studio site and hard on a business card. What does NIGHTJAR look like...

The AI Clothing Inspection System is an advanced automated quality control solution for garment and textile inspection. It leverages cutting-edge artificial intelligence technologies including multilingual OCR, deep learning vision models, and real-time object detection to ensure comprehensive product quality assurance. The system automates the detection of defects, verifies compliance with order specifications, and generates detailed inspection reports.


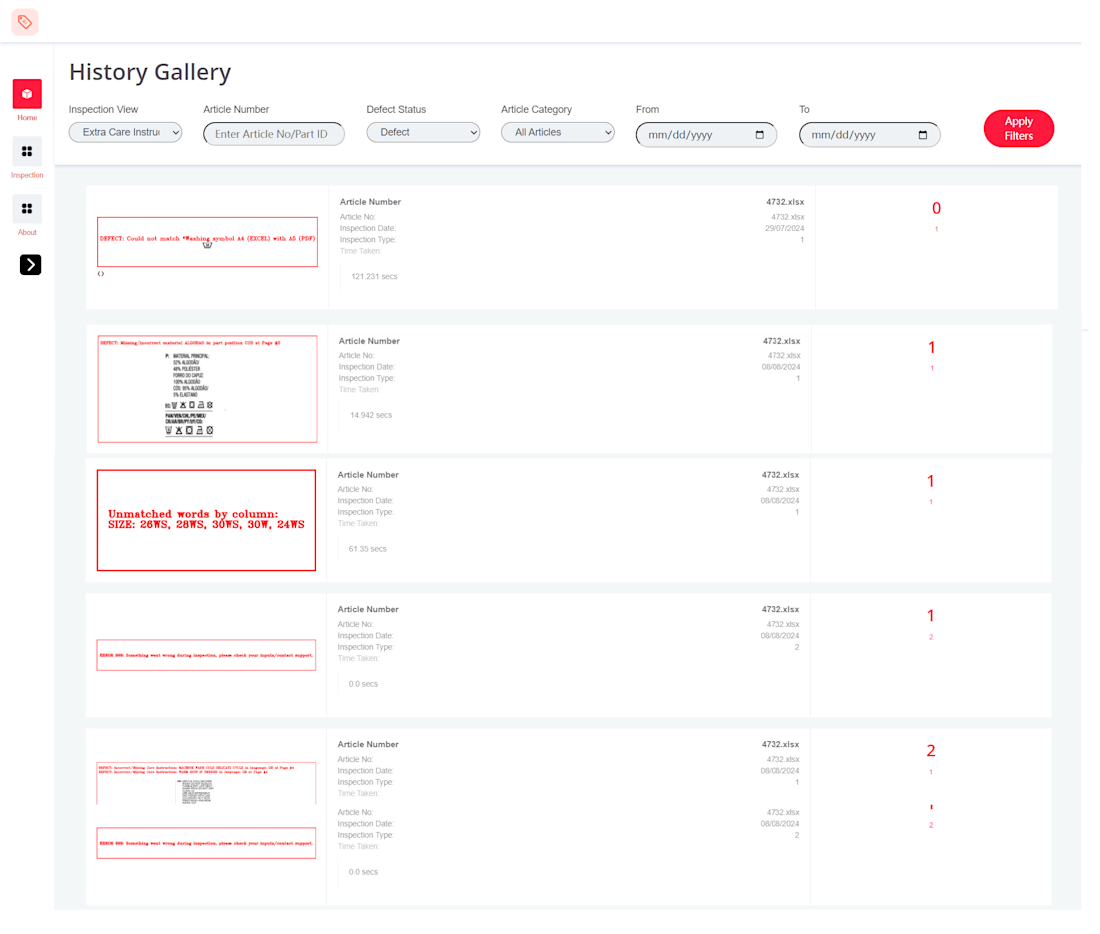
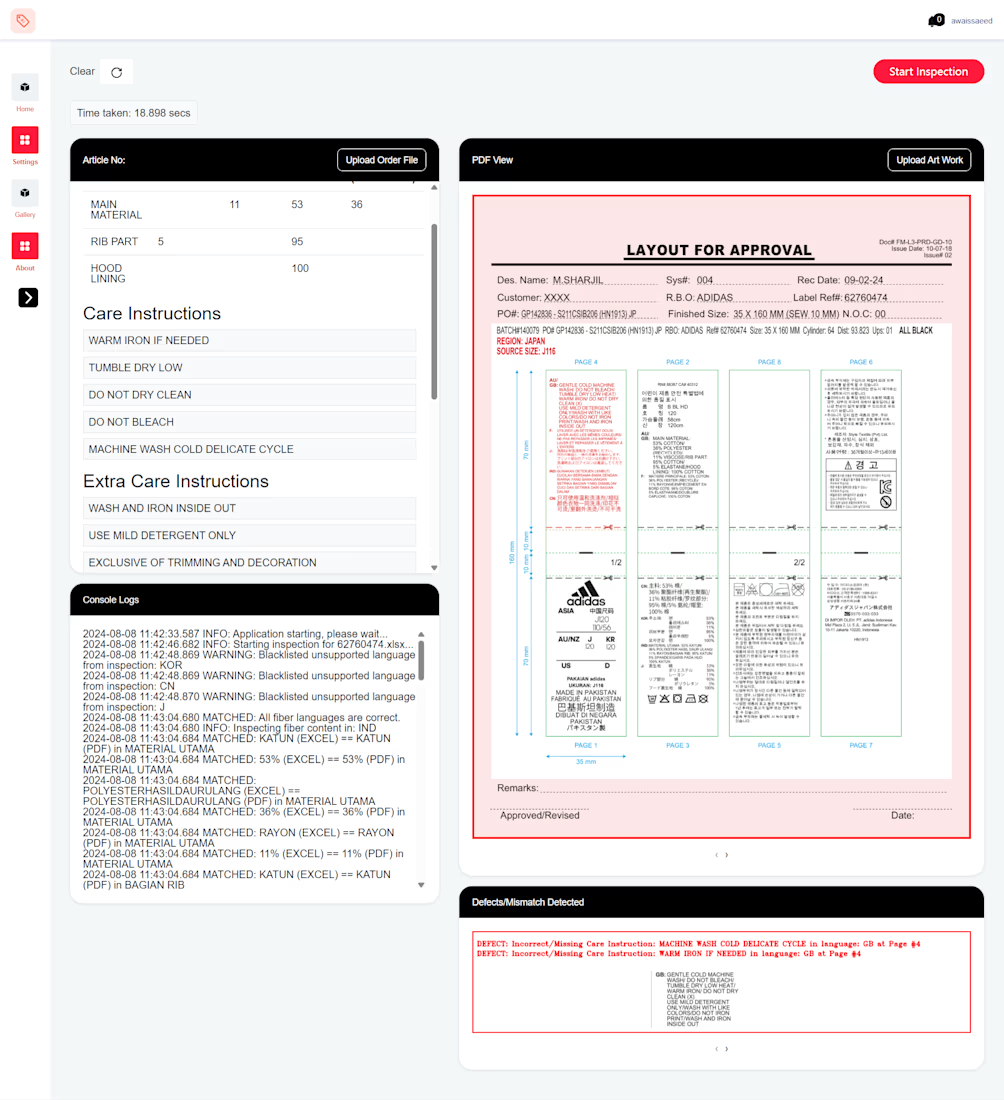
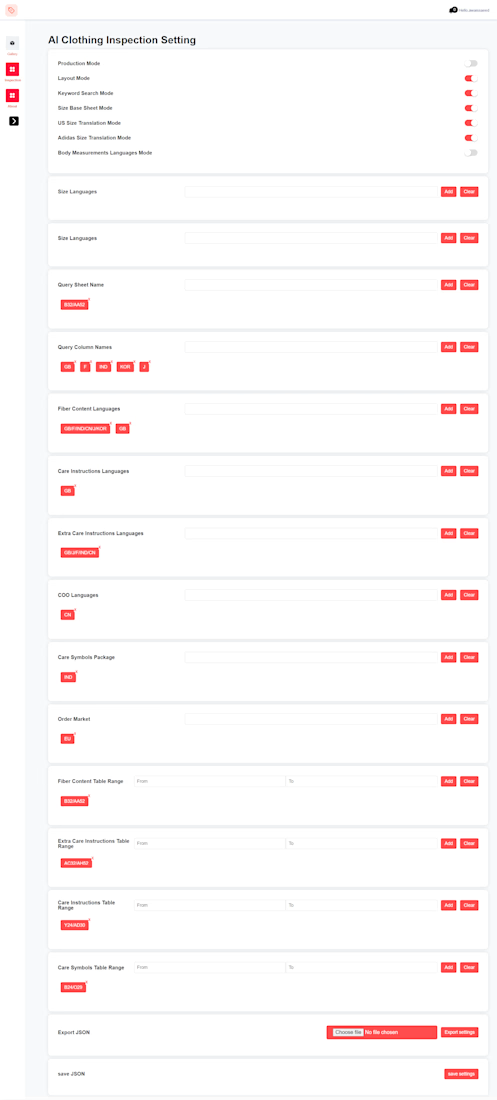
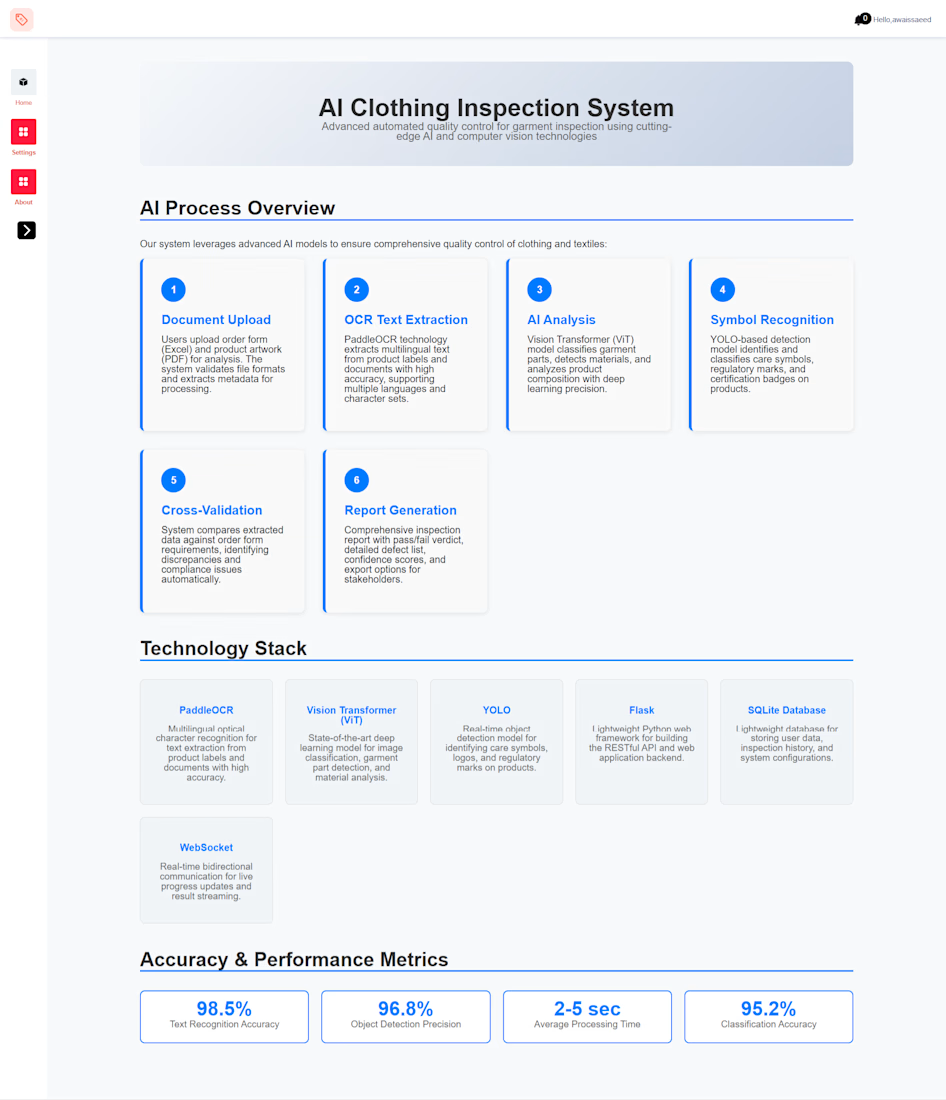

spotting garment defects with vision plus OCR on labels is a solid real-world use

Our latest case study is live! 📈
Meet Ahead.io, a crypto prediction market designed to make live probabilities, market activity, and trading data clear and easy to follow.


