
Not every variance deserves an investigation.
A budget says marketing expenses should be $20,000.
Actual spending comes in at $20,800.
That's a $800 variance.
Is it a problem?
Maybe.
But imagine the same business has a $5 million annual operating budget.
Spending $800 more may not deserve the same attention as a $20,000 unfavorable variance in another account.
This is where materiality becomes useful.
Instead of asking:
“Why is the number different?”
Ask:
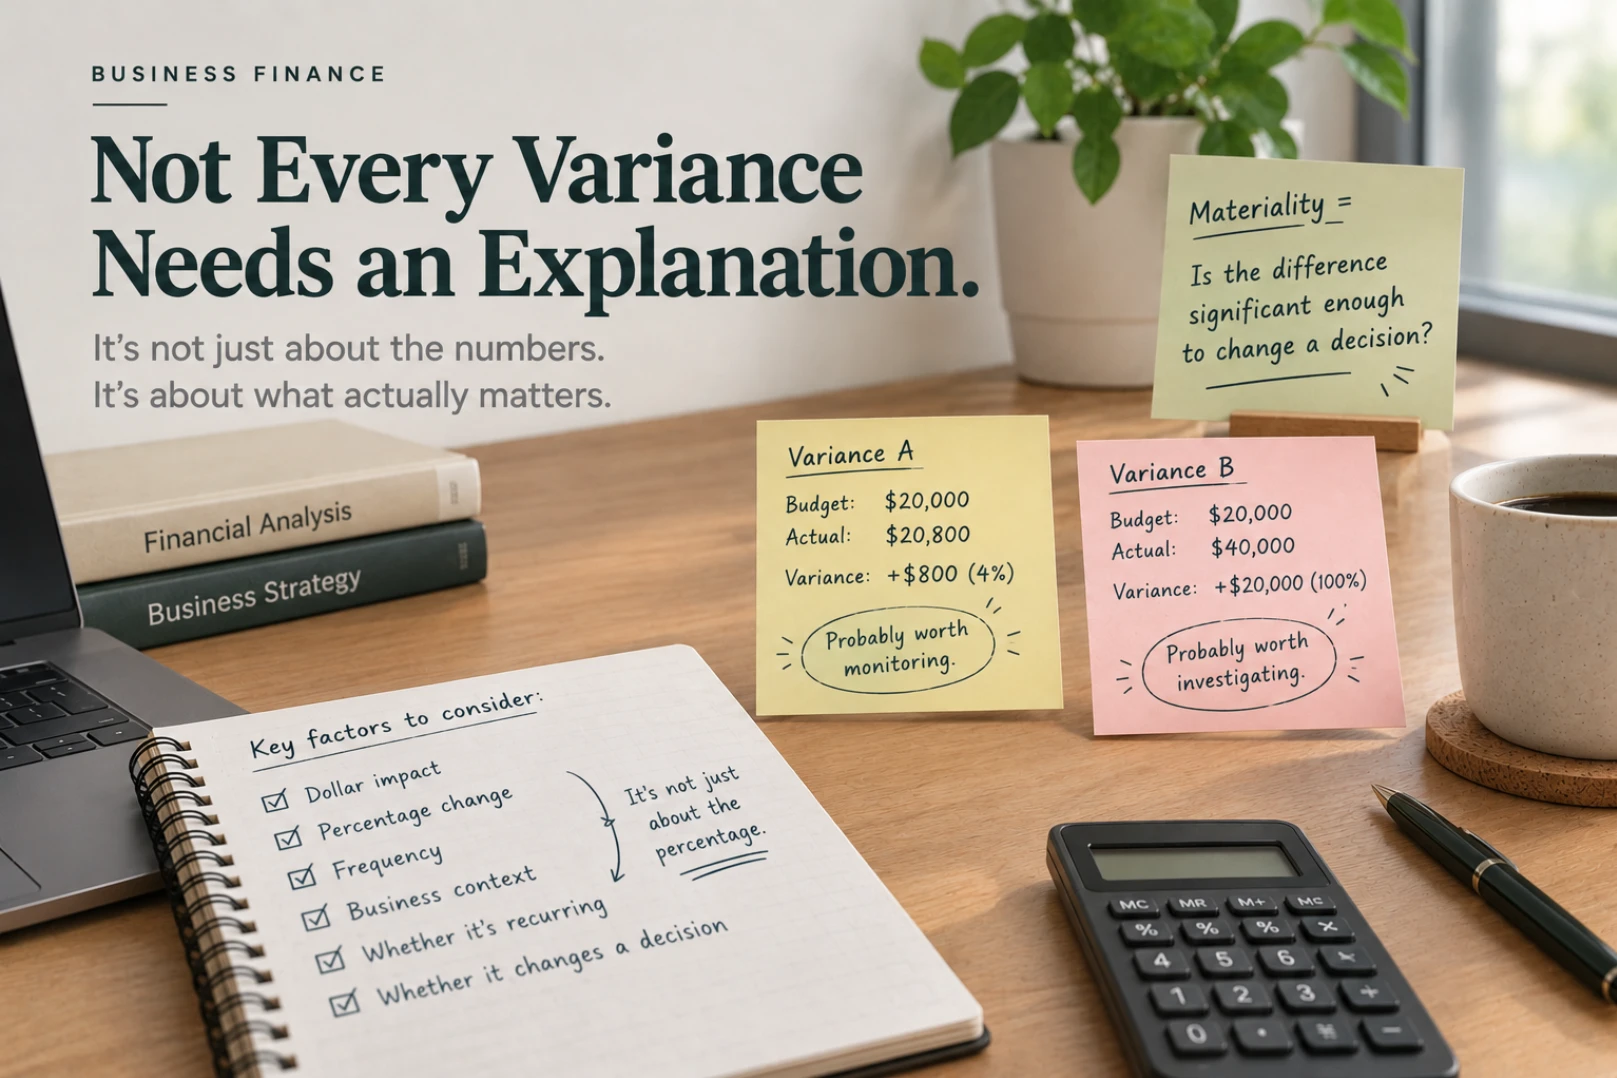
“Is the difference significant enough to change a decision?”
For example:
Variance A
Budget: $20,000
Actual: $20,800
Variance: +4%
→ Probably worth monitoring.
Variance B
Budget: $20,000
Actual: $40,000
Variance: +100%
→ Probably worth investigating.
But percentage alone isn't enough either.
A 50% variance on a $500 expense may matter less than a 5% variance on a $100,000 expense.
That's why a good variance review should consider:
→ Dollar impact
→ Percentage change
→ Frequency
→ Business context
→ Whether the variance is recurring
→ Whether it changes a decision
The goal of management reporting isn't to explain every number.
It's to identify the numbers that deserve attention.
Otherwise, finance teams can spend hours explaining small movements while missing the few variances that actually affect the business.
How does your team decide which variances are worth investigating?
#FPandA #FinancialAnalysis #ManagementReporting #BusinessFinance #VarianceAnalysis #Finance #BusinessStrategy #FinancialPlanning
0 likes · 0 views · Sep 24, 2026
Not every variance deserves an investigation. A budget says marketing expenses should be $20,000. Actual spending comes in at $20,800. That's a $800 variance...
