The network for creativity
Join 1.25M professional creatives like you
Connect with clients, get discovered, and run your business 100% commission-free
Creatives on Contra have earned over $150M and we are just getting started
Back to feedPost

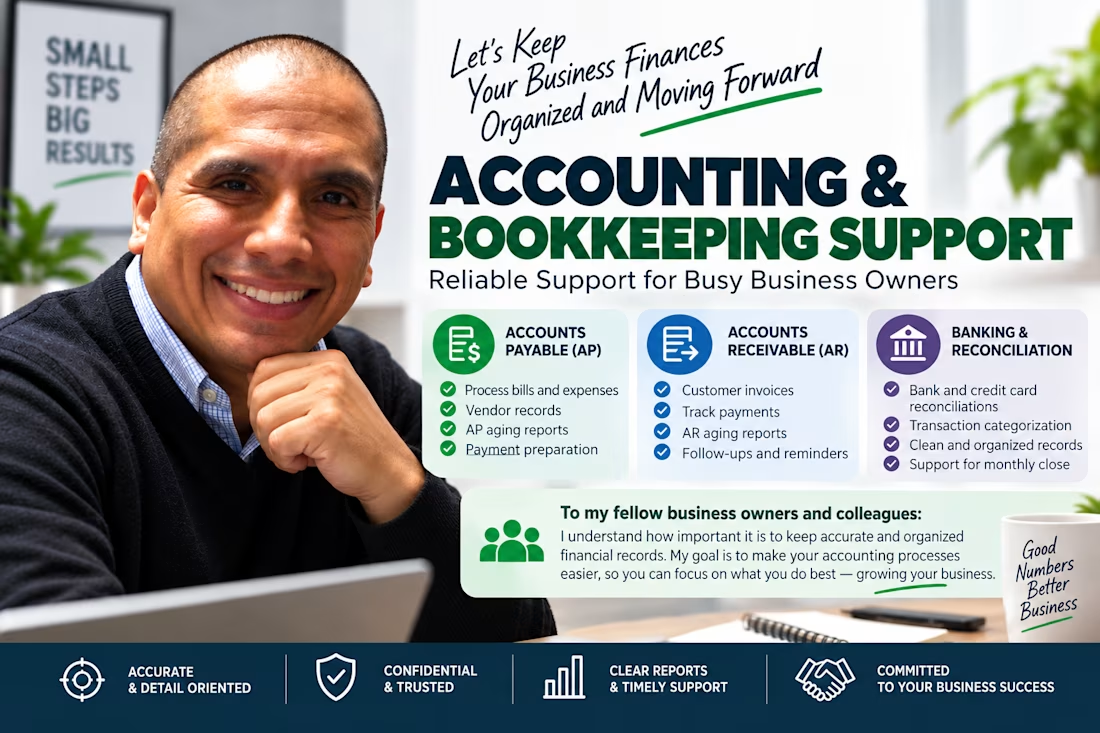
Need help keeping your business finances organized?
I provide reliable accounting and bookkeeping support to help small businesses maintain accurate records, track transactions, and stay organized.
My services include:
Accounts Payable (AP): Bill processing, vendor records, AP aging reports, and payment tracking.
Accounts Receivable (AR): Customer invoice tracking, payment records, AR aging reports, and follow-up support.
Banking & Reconciliation: Bank and credit card transaction categorization, reconciliation support, and organized financial records.
I work with attention to detail, confidentiality, and a commitment to accuracy and timely delivery. I also have QuickBooks Online training and certification.
To my fellow business owners and accounting professionals: If you need an extra pair of hands to keep your books organized and your accounting processes running smoothly, I'd be happy to connect.
Let's make bookkeeping simpler, one step at a time.


The network for creativity
Join 1.25M professional creatives like you
Connect with clients, get discovered, and run your business 100% commission-free
Creatives on Contra have earned over $150M and we are just getting started



Related posts

I am calling this the "Mistake post".
Wait. Did I post this by mistake?....
No, I promise. This is a bookkeeping post about the mistakes that quietly cost business owners money. There are many, so I will take one mistake at a time. This post is only about Mistake 1.
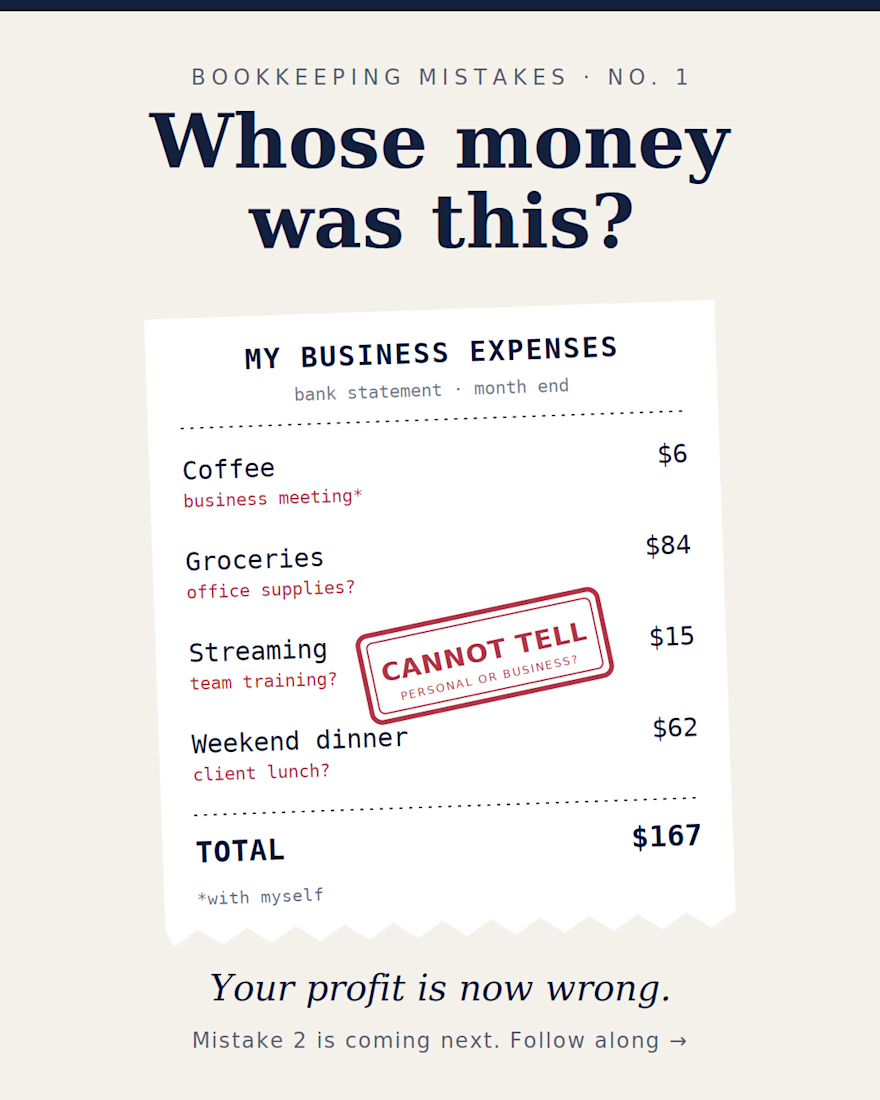
Mistake 1: Mixing personal and business spending One coffee here, one grocery bill there, and by the end of the month nobody knows whose money was spent. Yes, that coffee was a "business meeting". With yourself.
It looks small. It is not. Here is what it quietly does to your business:
Your profit becomes wrong. Personal costs sit inside business expenses, so the numbers do not show how the business is really performing.
Your bank reconciliation becomes slow. Every personal payment needs an explanation before your books can match the bank statement.
Your tax work becomes harder. When costs are mixed, it is difficult to prove which expenses truly belong to the business.
You lose clarity. You cannot tell how much the business earned and how much you took out for yourself.
Check your statement once a week. Small habit. Clean books. Much less stress at year end.
Mistake 2 is coming in the next post, so follow along so you do not miss it.


A client asked me last week: “I paid my insurance in full in October. Why is the whole amount not showing in my expenses?”
Fair question. Honestly, this is one of the most common things business owners ask me.
Here’s how I explained it. When you pay for a full year of insurance, the money leaves your bank on day one. But the insurance company protects you for 12 months, not one day. So you only use a small part of it at the start. The unused part isn’t an expense yet. It’s cover you have already paid for and still have.
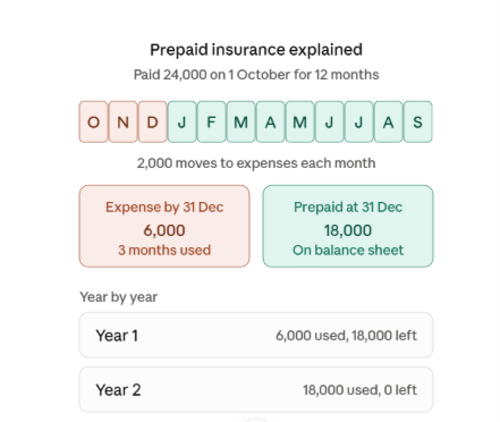
Say you pay 24,000 on 1 October for a 12 month policy. Each month, 2,000 moves into expenses.
By 31 December, you have used 3 months:
Expense so far: 6,000
Still unused: 18,000
That 18,000 stays on the balance sheet as prepaid.
The client still wasn’t fully sure from the numbers alone, so I showed them year by year:
Year 1 (Oct to Dec): 6,000 used, 18,000 still prepaid
Year 2 (Jan to Sep): 18,000 used, 0 left
By the end of the policy, the full 24,000 has moved into expenses. Nothing is lost. It just moves a little each month, as you use the cover.
That’s when it clicked for them.
Rent paid in advance, software subscriptions, annual membership, visa fees and licence fees all work the same way. Pay now, use over time, expense a little each month.
If your bookkeeper says “prepaid” and you just nod, ask them for a schedule like this. It’s your money, you should be able to see where it is.
A designer asked me: “I only send invoices. Do I really need a bookkeeper?”
Fair question. Most designers think bookkeeping is only for big companies.
But the moment you take client money, you run a business.
Say you earned 60,000 this year. It feels like profit. Now look closer:
Income: 60,000
Software: 6,000
Equipment: 8,000
Contractors: 5,000
Fees: 3,000
Tax to set aside: 10,000
Real money left: 28,000
Without records, you think you have 60,000. You have less than half.
A bookkeeper helps you:
Track every invoice
Record every expense
Keep personal and business money apart
See your real profit each month
You focus on the design. We make sure the numbers behave.
This is part of my contra series, where I explain accounting without the jargon.