The network for creativity
Join 1.25M professional creatives like you
Connect with clients, get discovered, and run your business 100% commission-free
Creatives on Contra have earned over $150M and we are just getting started
Back to feedPost

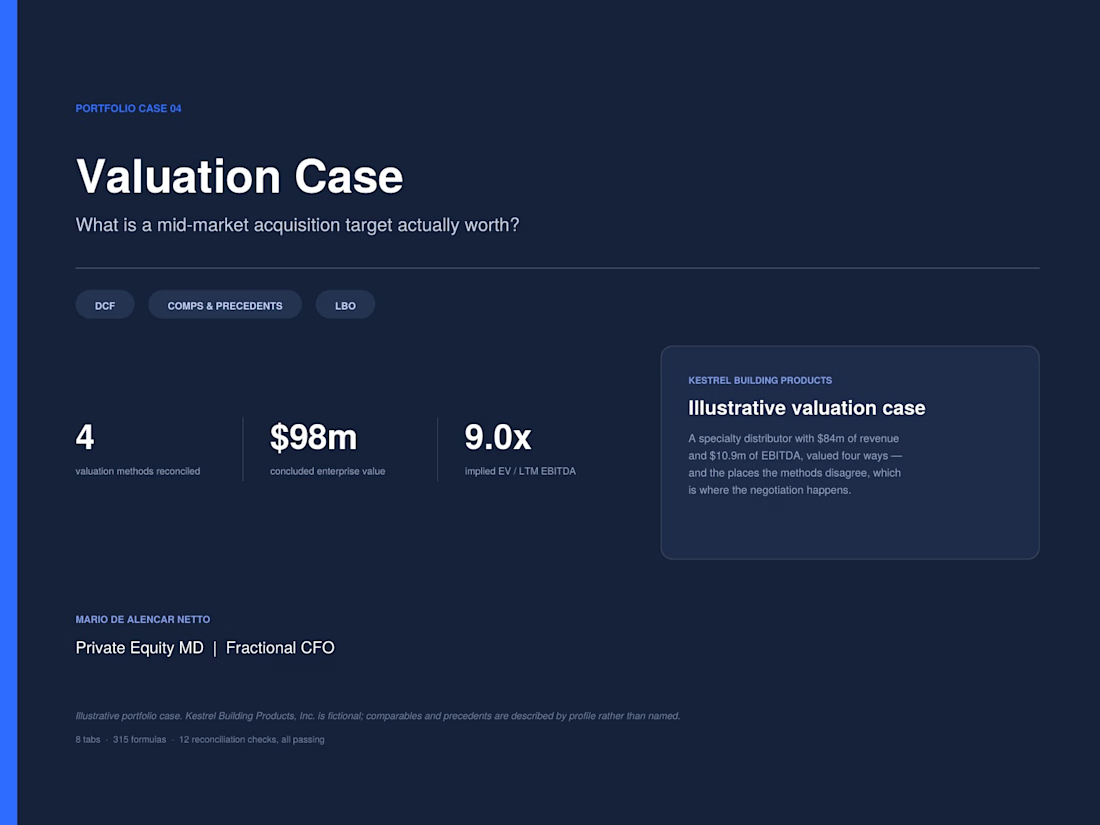
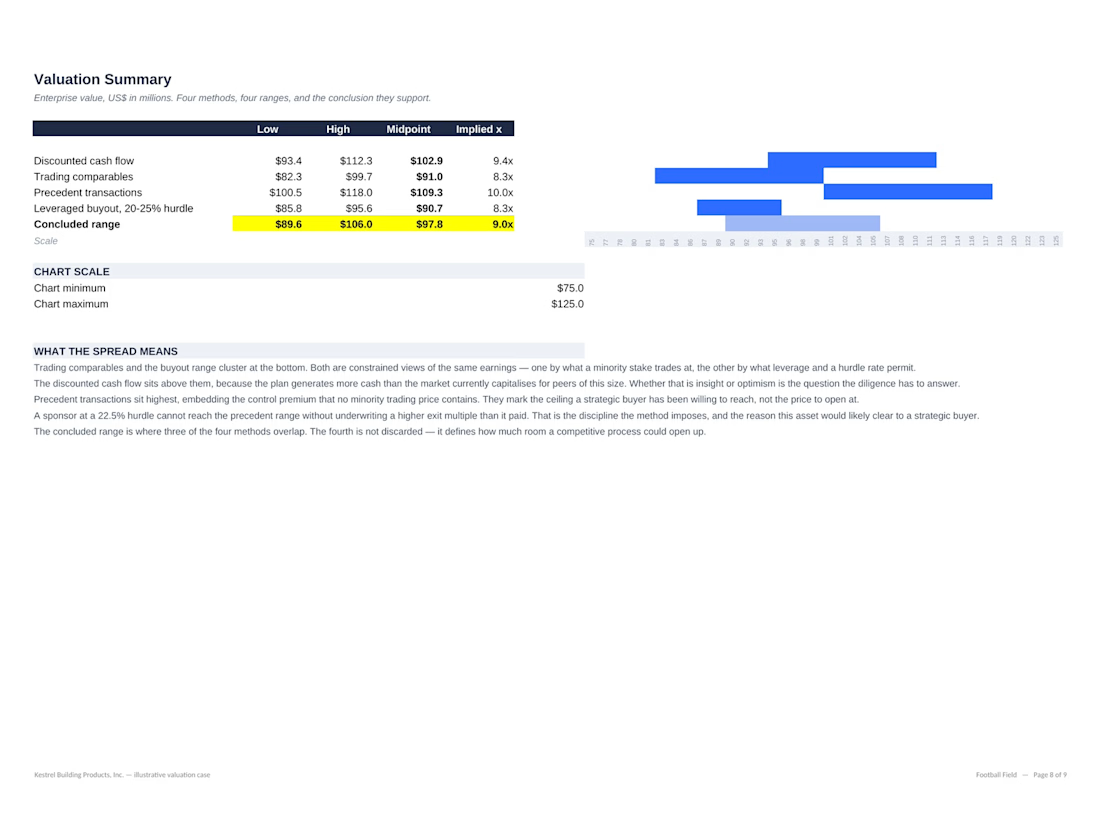
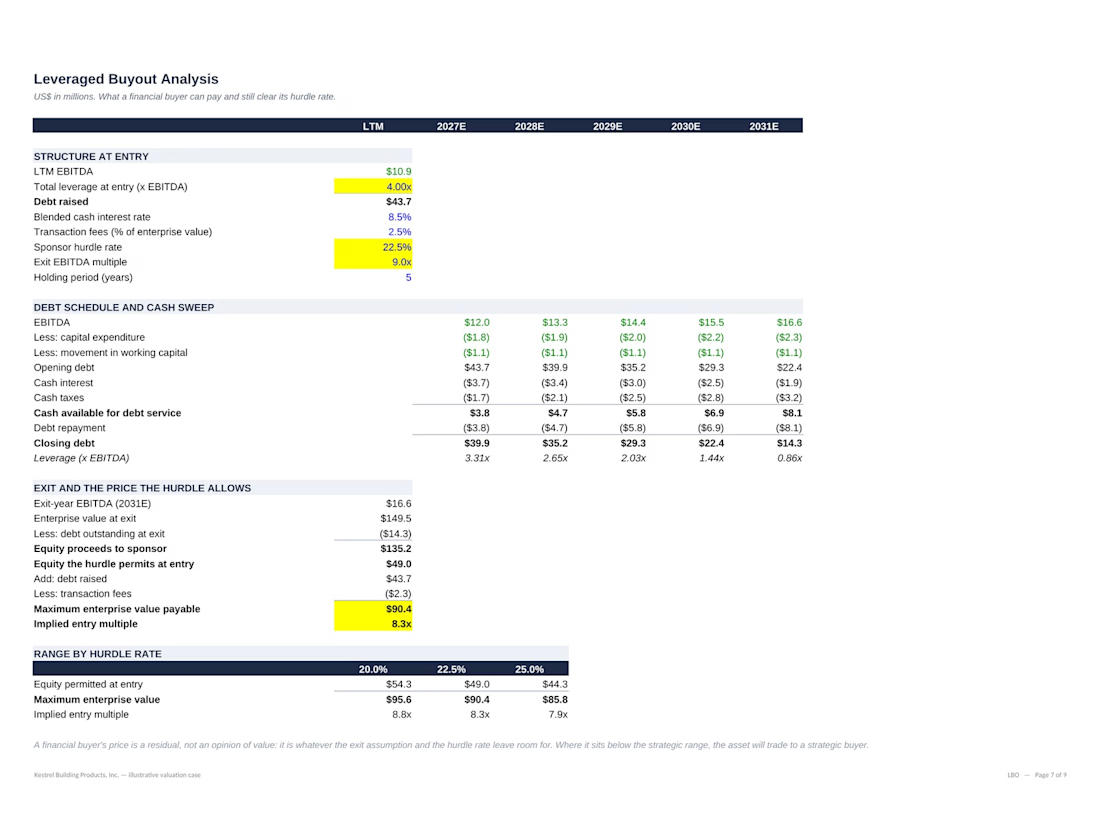
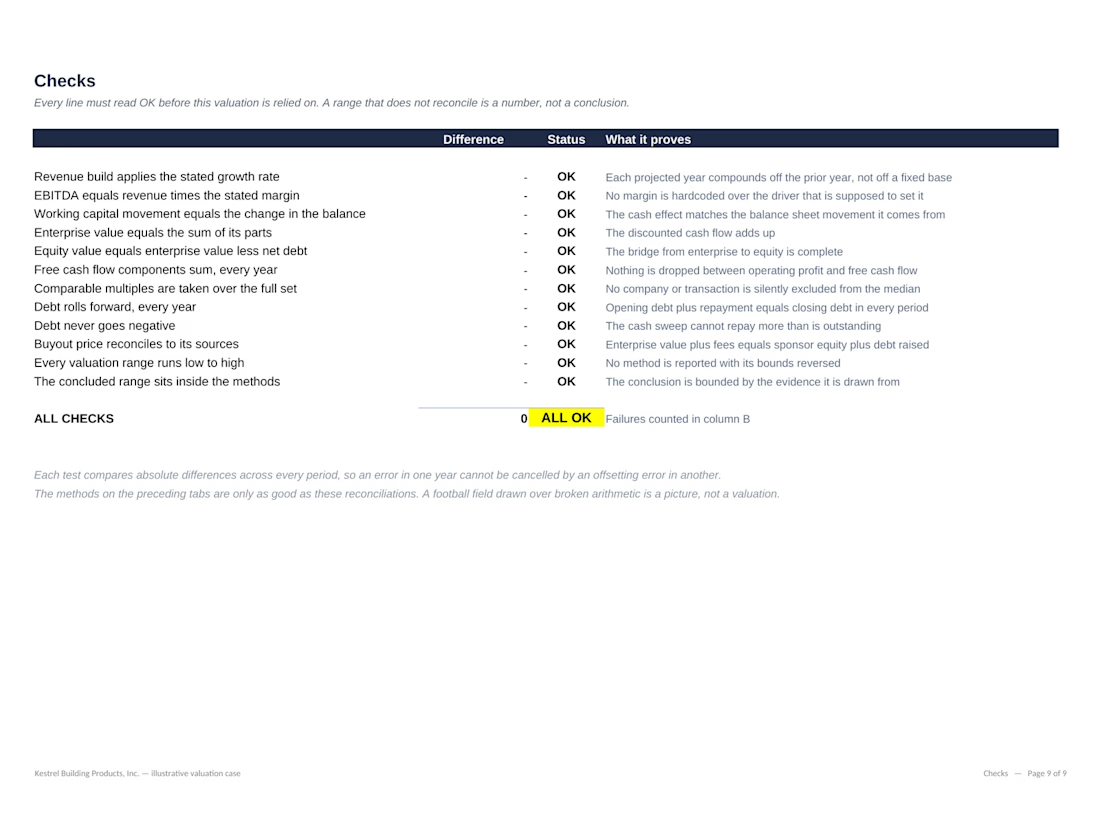
Multi-method valuation of a mid-market acquisition target — a specialty building products distributor with $84m of revenue and $10.9m of EBITDA. Discounted cash flow with a built-up WACC, trading comparables adjusted for size, precedent transactions, and an LBO solved backwards from the sponsor's hurdle rate. The four methods disagree, and the football field shows where — because that gap is the negotiating range. 12 reconciliation checks. Kestrel Building Products is fictional; comparables and precedents are described by profile rather than named.


The network for creativity
Join 1.25M professional creatives like you
Connect with clients, get discovered, and run your business 100% commission-free
Creatives on Contra have earned over $150M and we are just getting started
Challenges
View all


Related posts

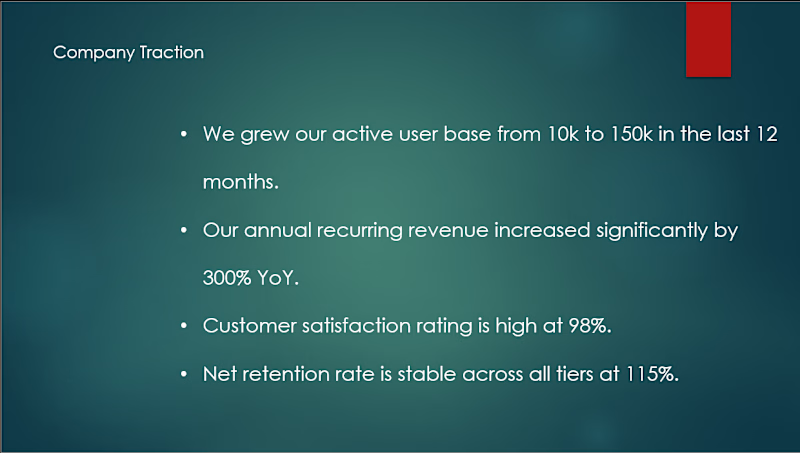
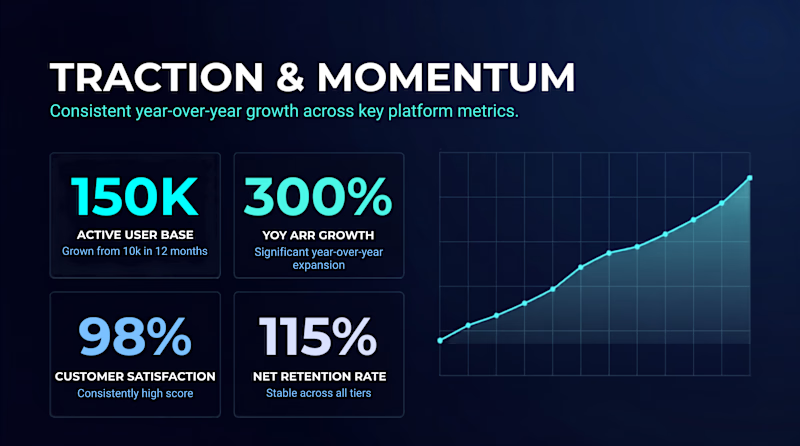
Transforming cluttered traction bullets into a high-impact investor slide
0 voted
0%
2 voted
100%
2 votes
Closed


the green line on that traction slide is so easy to read

From the vault — a property valuation campaign for TLC London.
Motion-led storytelling to make a complex message simple and engaging.
videoeditormotiondesignsocialadsMotion DesignVideo EditingVideo Post-ProductionAdobe After EffectsAdobe Media EncoderAdobe Premiere Pro


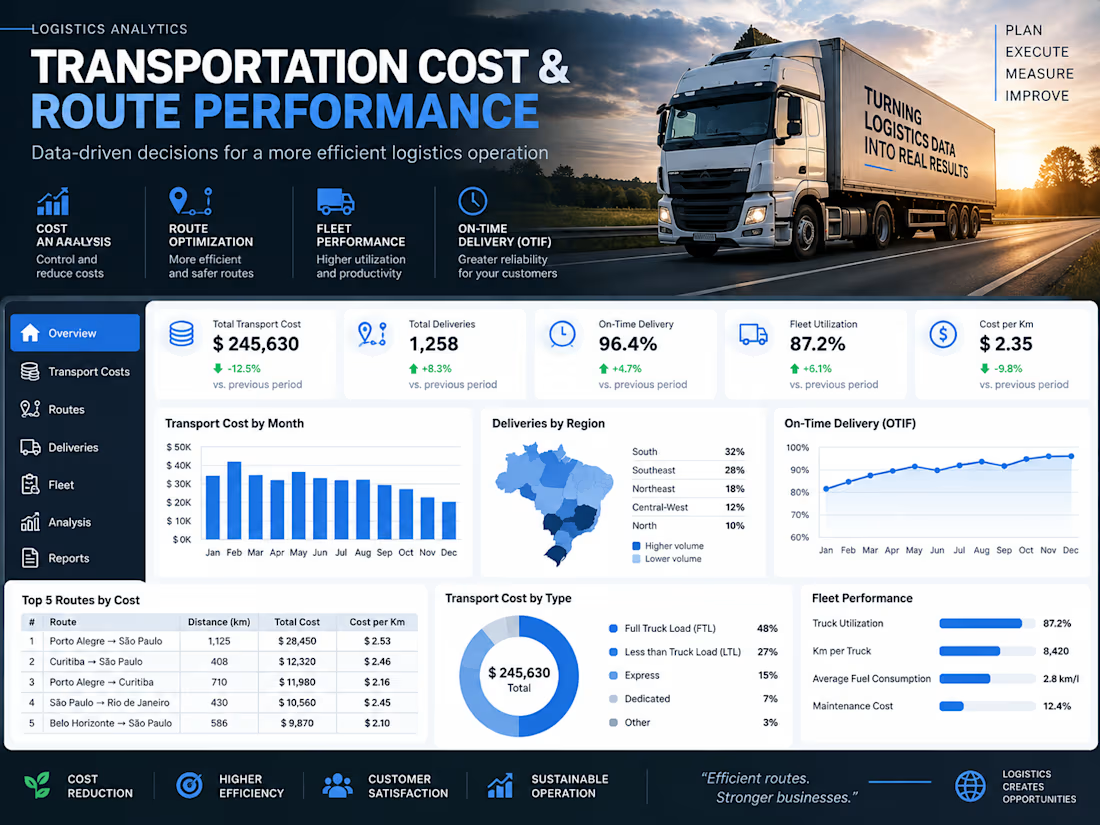
I help businesses turn logistics data into actionable insights.
I recently developed a Transportation Cost & Route Performance Dashboard focused on transportation costs, OTIF, route performance and fleet utilization.
Built with simulated data to demonstrate my skills in Logistics Analytics and Excel.
Available for freelance projects in Logistics, Supply Chain, Inventory and Data Analysis.