Default risk for a loan book with zero defaultsNahom Behailu Geremew
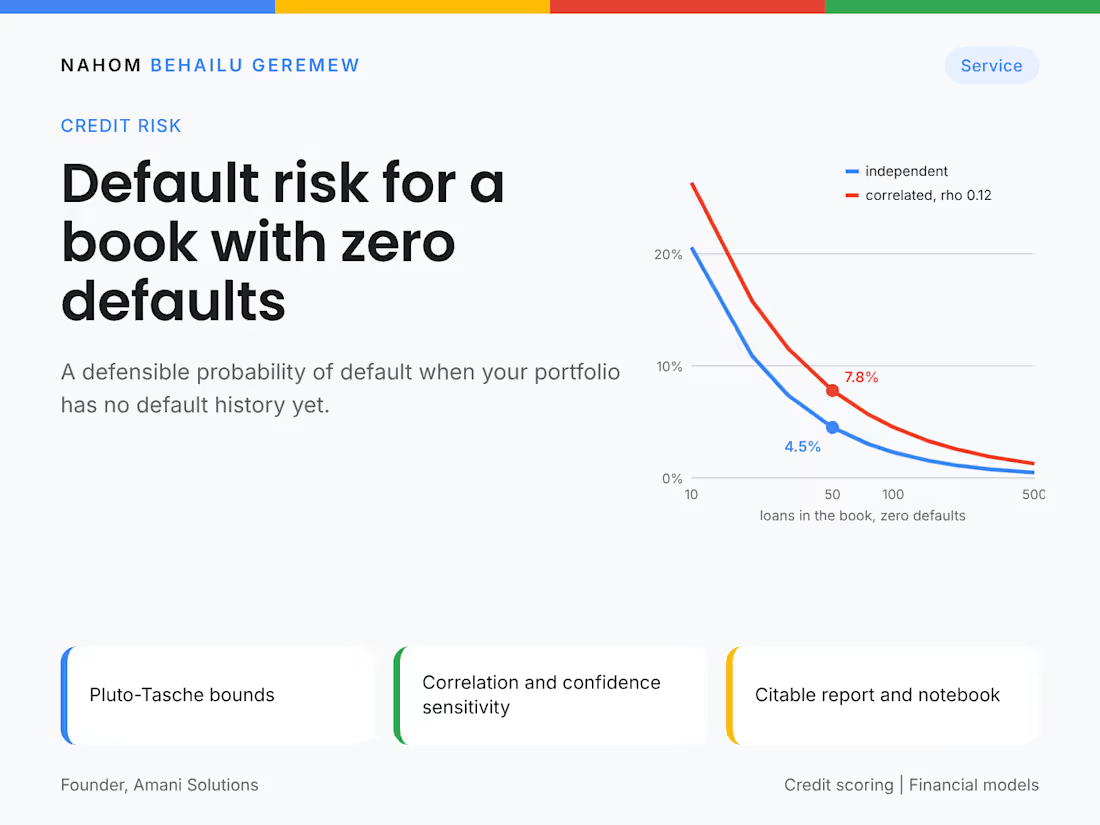
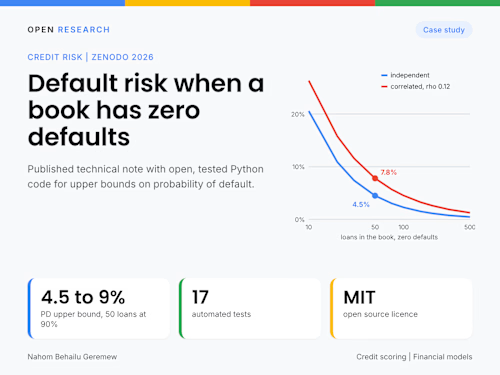
No defaults yet does not mean zero risk, and your regulator, insurer and investors know it. I give you a defensible upper bound on probability of default for your portfolio, using the methods from my published technical note.
What you get
Pluto-Tasche bounds with and without default correlation
Bayesian and beta-binomial cross-checks
Sensitivity to confidence level and asset correlation
A short, citable report and the Python notebook
Proof of method
Based on my open-source work, DOI 10.5281/zenodo.23864351, with tested code on GitHub.
FAQs
Example work
Nahom Behailu's other services
Starting at$349
Duration1 week
Tags
Financial Analyst
Service provided by
Nahom Behailu Geremew Addis Ababa, Ethiopia
Default risk for a loan book with zero defaultsNahom Behailu Geremew
Starting at$349
Duration1 week
Tags
Financial Analyst
No defaults yet does not mean zero risk, and your regulator, insurer and investors know it. I give you a defensible upper bound on probability of default for your portfolio, using the methods from my published technical note.
What you get
Pluto-Tasche bounds with and without default correlation
Bayesian and beta-binomial cross-checks
Sensitivity to confidence level and asset correlation
A short, citable report and the Python notebook
Proof of method
Based on my open-source work, DOI 10.5281/zenodo.23864351, with tested code on GitHub.
FAQs
Example work
Nahom Behailu's other services
$349