Python Strategy Backtesting and Performance ReportKyde Khumalo
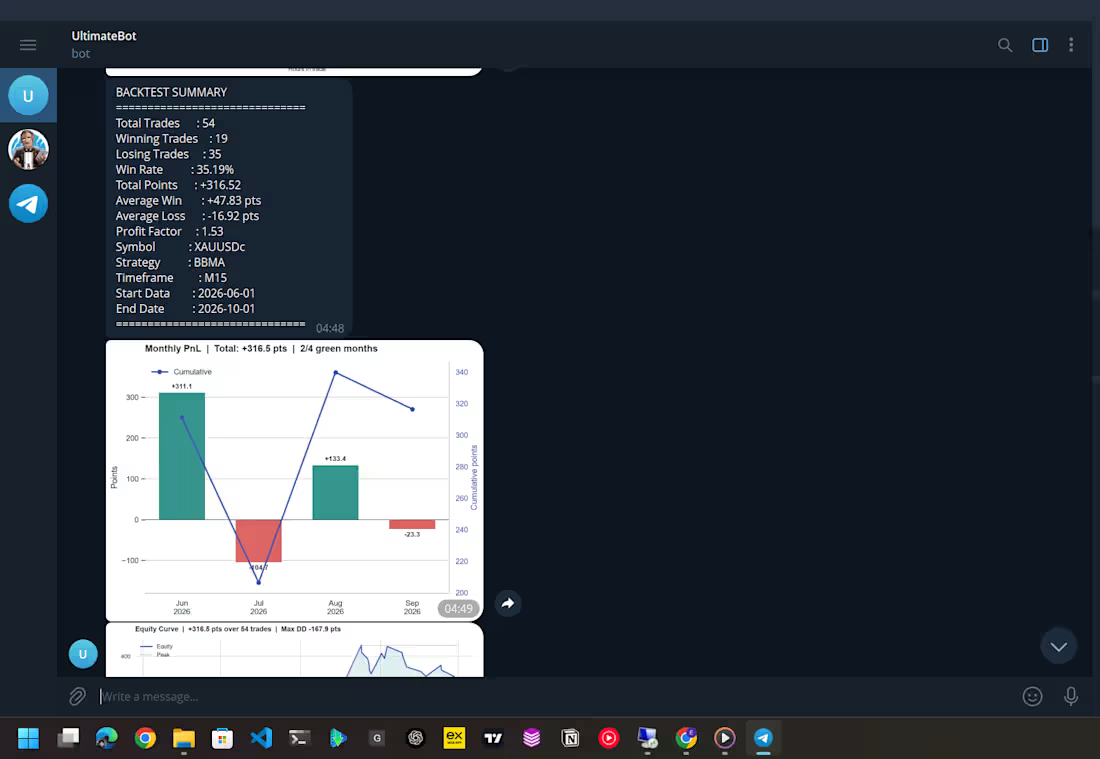
I build Python backtesting engines that run your strategy on historical price or tick data and show you exactly how it would have performed. You get a clean report with win rate, profit factor, drawdown, average trade, and an equity curve, plus a full trade log so every entry and exit can be audited. Parameters are configurable, so you can rerun tests with different settings yourself. Results can be delivered as a Jupyter notebook for easy reading.
FAQs
Kyde's other services
Starting at$120
Duration5 days
Tags
Backtesting
Python
Quantitative Analysis
Trading Strategy
Service provided by
Kyde Khumalo Durban, South Africa
- 1
- Followers
Python Strategy Backtesting and Performance ReportKyde Khumalo
Starting at$120
Duration5 days
Tags
Backtesting
Python
Quantitative Analysis
Trading Strategy
I build Python backtesting engines that run your strategy on historical price or tick data and show you exactly how it would have performed. You get a clean report with win rate, profit factor, drawdown, average trade, and an equity curve, plus a full trade log so every entry and exit can be audited. Parameters are configurable, so you can rerun tests with different settings yourself. Results can be delivered as a Jupyter notebook for easy reading.
FAQs
Kyde's other services
$120