The network for creativity
Join 1.25M professional creatives like you
Connect with clients, get discovered, and run your business 100% commission-free
Creatives on Contra have earned over $150M and we are just getting started
Back to feedPost

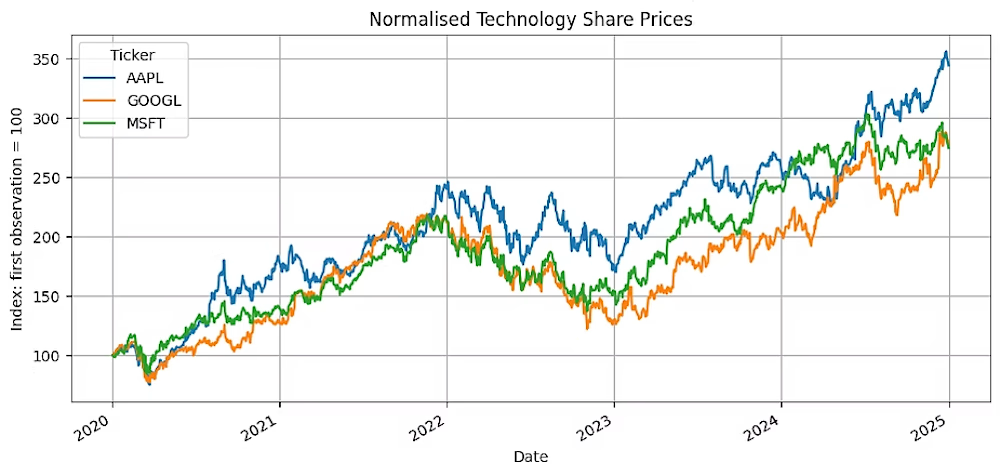
I ask the question most forecasting projects skip: is this data even stable enough to model? Using five years of Apple, Microsoft, and Alphabet share prices, I test for stationarity with the Augmented Dickey-Fuller test, compare raw prices against daily log returns, and run structural-break analysis to show how major market events shift underlying relationships. The result is a practical case for why financial models should start with understanding data behavior — not with prediction. Built in Python using real Yahoo Finance data.

The network for creativity
Join 1.25M professional creatives like you
Connect with clients, get discovered, and run your business 100% commission-free
Creatives on Contra have earned over $150M and we are just getting started

Challenges
View all


Related posts


Admivo.in — Full-Stack Product
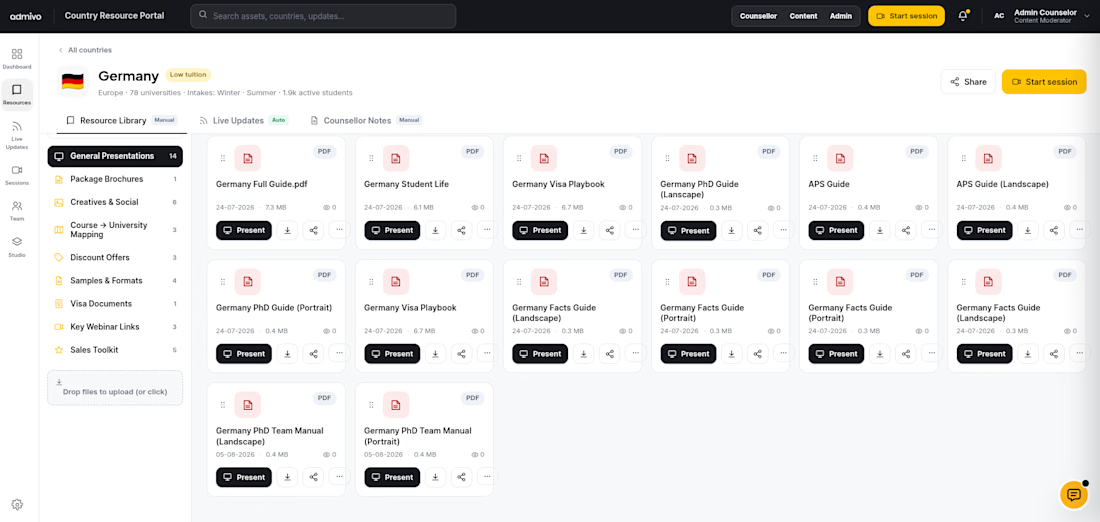
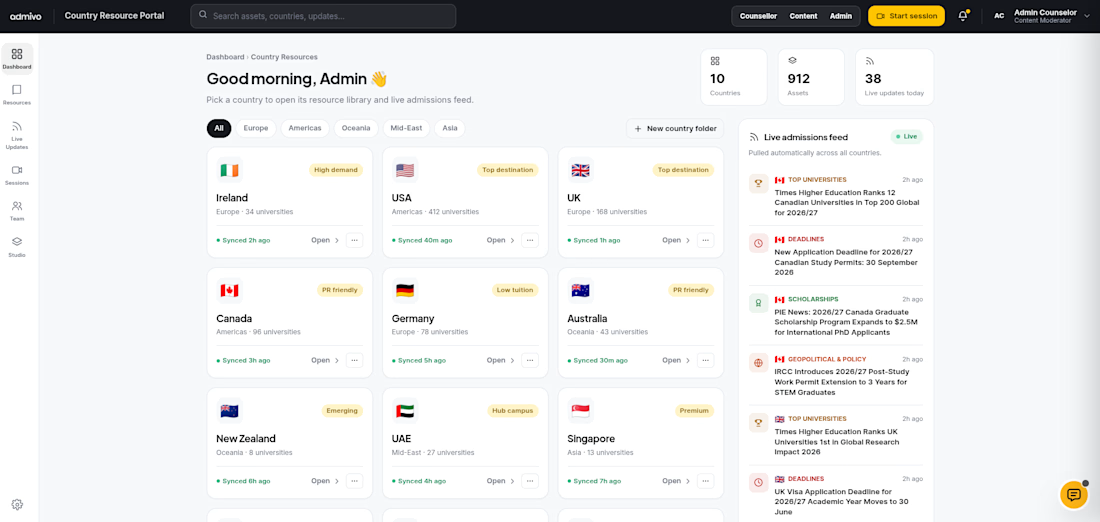
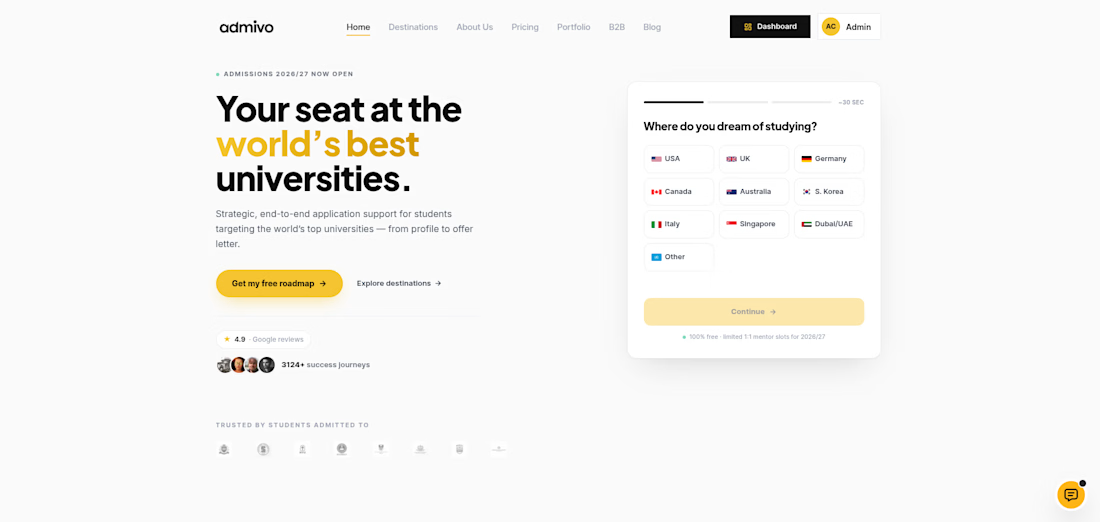
Built the complete Admivo.in ecosystem from scratch for a foreign education consultancy, covering the student-facing platform and internal operations. The system includes country/destination discovery, application journey, counsellor workflows, resource libraries, live admission updates, document management, sessions, and an admin dashboard for managing the entire ecosystem.